Best Rates for Personal Loans for High Income Individuals
Last updated: 2026-10-16
Accessing liquid capital can feel like hitting a brick wall for those at the top of the income ladder. Even when your tax filings shout your success, finding a bank that actually grasps your intricate cash flows feels like an endless marathon. It is not merely about securing funds; it is about finding a financial ally.
You deserve a lender that recognizes your level of sophistication. For surgeons, high-level engineers, or corporate executives, the standard «one-size-fits-all» math used by many lenders often falls flat. These rigid algorithms frequently overlook the true depth of your personal wealth.
Your actual net worth might be tied up in seasonal bonuses, stock options, or deferred compensation. Since these elements don’t always pop up clearly on a standard pay stub, basic credit models often misinterpret your profile. This mismatch can lead to frustratingly high rates or outright denials, despite your massive assets.
Selecting the ideal lender involves much more than just hunting for the lowest interest rate. You must weigh the speed of the capital delivery against the flexibility of the repayment schedule. In a world moving this fast, a clunky digital interface can be a massive headache for anyone with significant holdings.
Consider a scenario where you are ready to pull the trigger on a private equity play or a new property. If you have to spend three days wrestling with a legacy bank’s paperwork, the window of opportunity might slam shut. For the modern professional, friction in the application process is a total dealbreaker.
Our selection highlights providers that strike a perfect balance between rapid capital deployment and the unique requirements of wealthy borrowers. We have prioritized firms that lead with digital-first technology to ensure your momentum never falters. These are the lenders that move as quickly as you do when a deal arises.
- Discover
- Avant
- JetzLoan
- OneMain Financial
- LendingPoint
- Upgrade
Our Methodology for Assessing Premium Lenders
When we set out to vet these institutions, we kept the unique profile of affluent borrowers at the forefront. It isn’t just about interest rates; it is about access to substantial capital without the headache of pledging your home or assets as collateral. For many in the top tax brackets, the ability to leverage upcoming salary spikes or existing portfolios is essential.
We prioritized institutions that respect the sanctity of a credit score. This means searching for firms that employ «soft pulls» during the preliminary pre-qualification phase. Such a feature allows you to test the waters and see what you qualify for without leaving a permanent mark on your credit history.
Testing the waters without risk is a luxury we believe every high-earner deserves. Why should a simple inquiry jeopardize your rating? Our selection process leaned heavily toward lenders that offer this level of digital discretion and ease of use.
Time, as they say, is money, and for our target demographic, it is everything. We analyzed how quickly cash actually hits your bank account after the ink dries. If a real estate deal pops up on a Tuesday, you can’t afford to wait a week for a bank to wake up and process your request.
Consequently, our rankings favored providers capable of delivering funds in as little as one hour or, at the very least, within a twenty-four-hour window. Speed is the heartbeat of strategic investing. A slow lender is a useless lender when a lucrative opportunity is staring you in the face.
Transparency was the third pillar of our investigation. We scoured digital applications to ensure they weren’t a labyrinth of fine print. If a company tucks an «origination fee» away in a dense, twenty-page document, they didn’t make our cut. We want clarity, not a scavenger hunt for hidden costs.
Finally, we looked at whether these loans could actually grow with your lifestyle. A loan that caps out at $5,000 might help you fix a leaky faucet, but it won’t help you consolidate a mountain of high-interest debt or fund a luxury renovation. We needed tools that match the magnitude of high-net-worth life.
Our search focused on lenders offering a significant ceiling, specifically targeting those that go well beyond the small-scale. We sought out thresholds of $30,000 or more to ensure the liquidity offered was truly transformative. For strategic planning, you need a heavyweight, not a lightweight, in your corner.
Evaluating Leading Financing Options
Finding the right match for your lifestyle is a bit like picking a tailored suit. You need the perfect fit for your specific financial goals. Some lenders offer lightning-fast speed, while others prioritize high borrowing ceilings for those with significant capital requirements.
Comparing these institutions side-by-side helps you cut through the noise. Instead of wandering aimlessly through endless fine print, you can see exactly how much cash is on the table. It’s a vital step before you sign anything in blood.
Don’t let the fear of a bruised credit score keep you on the sidelines. Many of these providers allow you to peek behind the curtain without leaving a lasting mark on your report. This «soft» approach is a lifesaver for cautious planners.
The following breakdown provides a snapshot of the current market landscape. Use this as your compass when navigating the complex waters of personal credit. Remember, your personal situation is unique, so always verify the specifics directly with the source.
| Provider | Upper Limit | Processing Time | Rates & APR | Credit Score Effect |
|---|---|---|---|---|
| Discover | $40,000 | By the following workday | 6.99% – 24.99% | Zero cost for pre-qualifying |
| Avant | Consult website | Consult website | Consult website | Consult website |
| JetzLoan | $50,000 | Minimum 24 hours | Consult website | Hard inquiries avoided |
| OneMain Financial | $30,000 | Within 60 minutes | From 11.99% APR | No effect when checking |
| LendingPoint | $36,500 | Consult website | Consult website | No effect when checking |
| Upgrade | $50,000 | Rapid disbursement | Consult website | No effect when checking |
Top-Tier Lending Options for High-Income Professionals
1. Discover
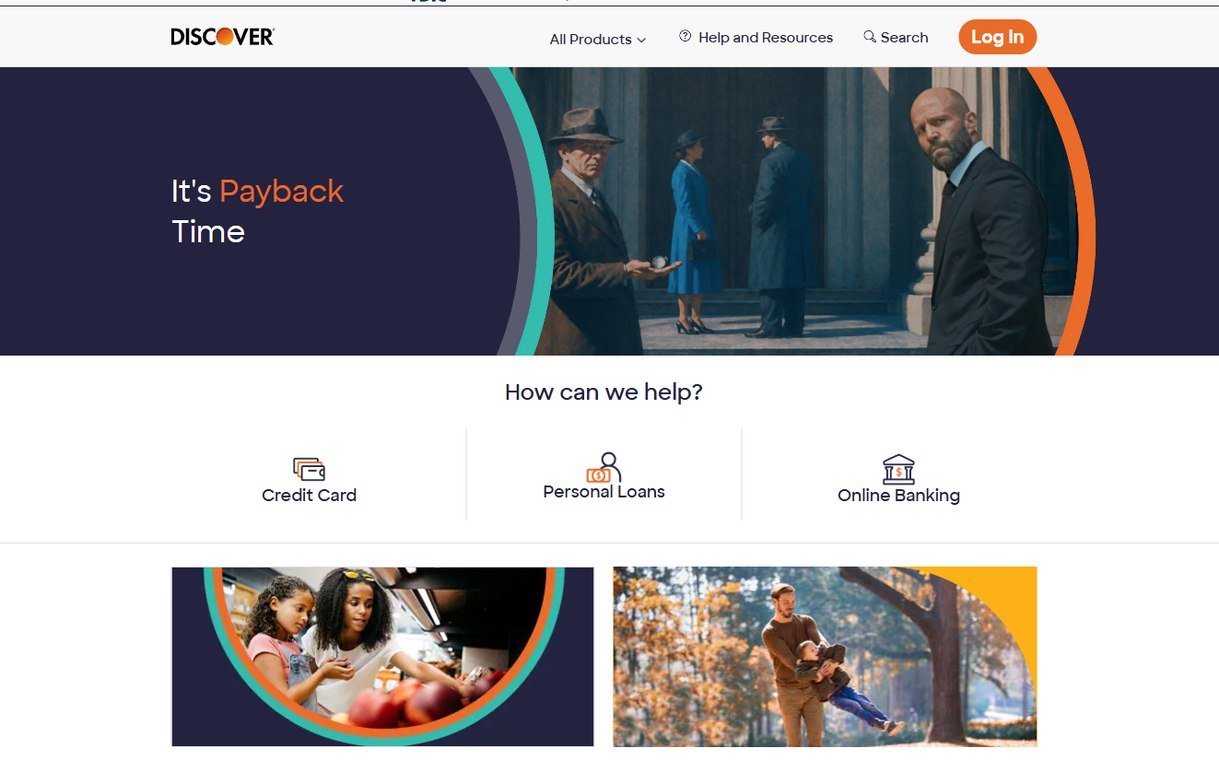
For those who sleep better knowing their finances are anchored by the stability of a massive, US-government-backed institution, Discover is a premier candidate. They provide straightforward personal loans, allowing you to borrow anywhere from $2,500 up to $40,000. It is a rock-solid choice for anyone prioritizing long-term institutional reliability over the latest market trend.
In an era where fintech startups often vanish or pivot on a whim, this company offers a sense of permanence that is hard to find elsewhere. Their digital experience is incredibly smooth, making it easy to see if you qualify before you commit to anything. This «soft look» is a lifesaver for busy executives who cannot afford to let their credit rating dip during the research phase.
Navigating their web platform feels like a breeze, with a layout designed to save you precious time. There is no need to wade through endless, useless menus to find what you need. For the high-flying professional whose schedule is packed tight, this efficiency is a true luxury that pays dividends in time saved.
Pros:
- Cash can arrive in your account by the next business day.
- Offers flexible terms and features no hidden fees.
- Checking your pre-approval won’t hurt your credit score.
Cons:
- Borrowing is capped at a maximum of $40,000.
2. Avant
Avant understands that life is rarely a straight line; it is a series of shifts and evolutions. Consequently, they specialize in providing adaptable financial solutions for individuals who are constantly moving the needle on their personal wealth. From consolidating existing debt to funding a home renovation, their product suite is quite diverse.
Think about a rising star in a law firm or medical practice; your debt-to-income ratio might look very different during a promotion than it did during residency. Avant provides a menu of options that can grow and change alongside your career trajectory. This flexibility is vital for maintaining financial agility as your income levels fluctuate.
They place a heavy emphasis on helpful support and versatile choices to help you master your financial journey. Whether you are tackling a sudden, unexpected cost or building a long-term plan to manage liabilities, their tools are built to simplify your life. It is a refreshing departure from the «cookie-cutter» approach of traditional lenders.
Pros:
- Tailored loan setups for a wide array of needs.
- Modern, intuitive digital tools for easy account oversight.
- Provides several different avenues for managing debt.
Cons:
- Detailed specifics regarding limits and terms aren’t always clearly stated upfront.
3. JetzLoan
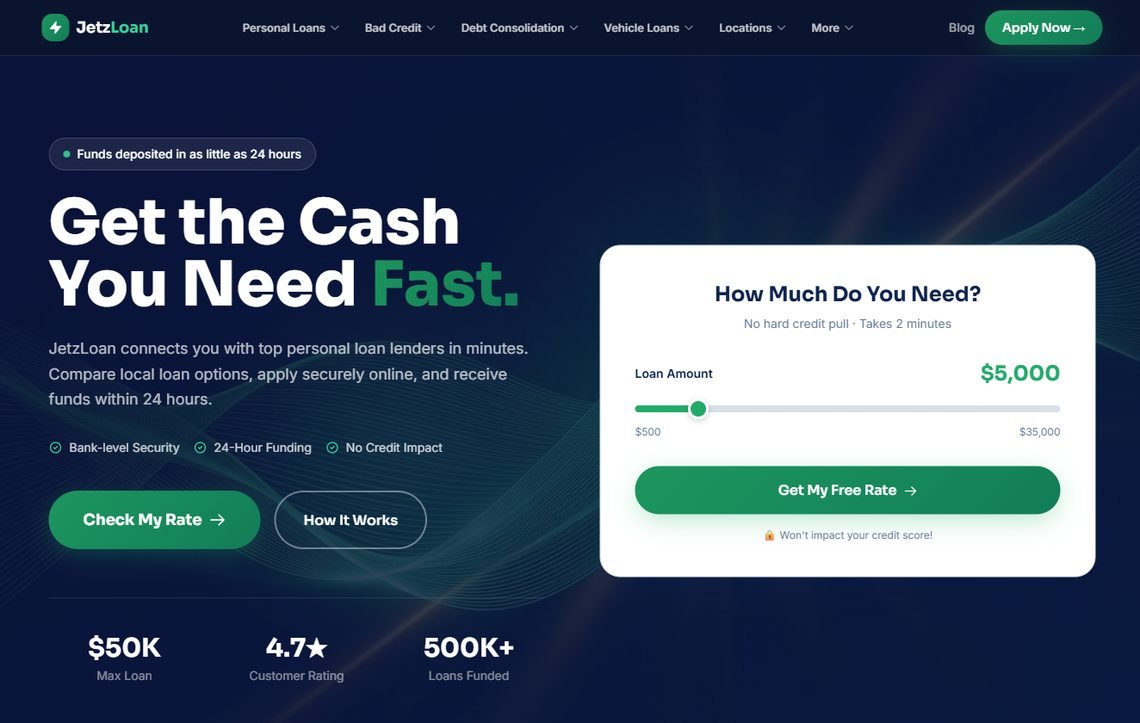
If you need capital at a moment’s notice, JetzLoan functions like a high-speed lane in a congested highway. They act as a conduit to top-tier lenders, often securing a connection in mere minutes. In many cases, you could see funds in your hands in as little as twenty-four hours, making them an ideal match for the fast-paced lifestyle of high earners.
Imagine a sudden, time-sensitive opportunity, such as a private placement or a quick-turnaround real estate auction. In those high-stakes moments, the velocity provided by this platform becomes a massive competitive edge. Waiting for a traditional bank to process paperwork would mean watching the opportunity slip through your fingers like sand.
The onboarding is remarkably efficient, requiring less than two minutes to breeze through the initial form. With a ceiling of $50,000, they meet significant financial demands without forcing a hard credit inquiry just to check your rates. This marketplace model saves you from the headache of applying to every bank individually, cutting down hours of tedious admin work.
Pros:
- Rapid disbursement, potentially hitting your account within a day.
- Initial rate comparisons won’t impact your credit score.
- A substantial maximum loan threshold of $50,000.
Cons:
- The service acts as a bridge to lenders rather than providing the funds directly.
4. OneMain Financial
OneMain Financial strikes a perfect balance for those who want digital speed paired with the reassurance of a human handshake. Their personal loan amounts range from $1,500 all the way up to $30,000, with interest rates starting at 11.99% APR. For emergencies where every minute counts, their ability to fund a loan just one hour after signing is nothing short of impressive.
In a world where everything is moving to the cloud, sometimes you just want to sit across a desk from a real person. With a network of 1,300 physical branches, you have the option to handle your business in person. This hybrid strategy is a major plus for high-net-worth individuals who demand the convenience of an app but want the security of a face-to-face meeting.
Having a local office to visit provides a layer of psychological comfort, especially when the math gets complicated. If you need to hash out intricate repayment schedules or provide specific documents that a purely digital algorithm might find difficult, a branch manager can help. It’s a safety net for your most important financial conversations.
Pros:
- Extremely fast turnaround, potentially in just sixty minutes.
- A massive network of physical locations for in-person help.
- Repayment timelines ranging from 24 to 60 months.
Cons:
- Interest rates on unsecured loans may outpace those of secured alternatives.
5. LendingPoint
LendingPoint is a versatile tool designed to cover the various milestones and surprises that life throws your way, from wedding festivities to medical bills. They provide loans between $1,000 and $36,500, serving as a perfect middle ground for those who need more than a tiny micro-loan but don’t require a massive mortgage.
Their underwriting process is far more sophisticated than the standard «check-the-box» methods used by basic lenders. Instead of just looking at a single number, they attempt to view the whole picture of your financial health. This nuanced approach helps ensure that the terms offered are actually reflective of your real-world stability.
The platform makes it easy to «window shop» for the best rate without any penalty to your credit profile. This is a critical feature for high-income earners who are often balancing multiple credit lines and need to be surgical about where they take on new debt. It allows you to compare costs with total precision and zero risk to your score.
Pros:
- Supports a wide variety of specific loan purposes.
- Check your potential rates without a credit score hit.
- Offers sizable loans with a $36,500 ceiling.
Cons:
- The maximum loan amounts are lower than those of niche lenders.
6. Upgrade
Upgrade serves as a comprehensive hub for the modern, tech-savvy consumer, offering personal loans that can reach up to $50,000. They have mastered the art of speed and seamless digital integration, allowing you to see what you qualify for in just a few minutes. It is a fantastic option for those looking to consolidate their financial life into one cohesive unit.
The strength of their platform lies in its robust ecosystem. You can manage your loans, savings, and checking accounts all within the same digital environment. Their technology-driven model is designed to remove the «friction of friction,» ensuring that there are as few hurdles as possible between your application and receiving your money.
This «all-in-one» strategy is particularly appealing to high earners who value efficiency above all else. By bringing your banking and lending under one roof, you gain a much clearer view of your total liquidity at any given moment. This transparency is absolutely essential for managing the sophisticated cash flow that comes with a high-income lifestyle.
Pros:
- Large borrowing capacity reaching up to $50,000.
- A unified system for savings, checking, and loans.
- Quick rate checks that leave your credit score untouched.
Cons:
- The sheer breadth of the ecosystem might feel complex for some users.
Leveraging Credit as a Financial Lever
High-net-worth individuals should stop thinking of personal loans as mere liabilities. Instead, view them as a sophisticated instrument for liquid capital deployment. When handled with precision, these funds act as a bridge toward significant wealth accumulation. It is all about timing and the clever deployment of borrowed funds.
Imagine you are standing on the sidelines of a lucrative deal. Perhaps it is a distressed real estate grab or a private equity play that requires immediate action. You cannot afford to wait for your seasonal bonus to clear or for a different asset to liquidate. This is where a loan steps in to provide instant liquidity.
In these scenarios, the math is simple. You weigh the interest expense against the projected returns of the opportunity. If the upside of the investment dwarfs the cost of the debt, you are not just borrowing money; you are buying time. It is a calculated move to ensure you never miss a golden opportunity due to a temporary cash crunch.
Tax optimization is another way to play the game. While you won’t see the same tax deductions as you would with mortgage interest, these loans serve a vital purpose in cash flow management. They help you navigate the choppy waters of high-tax years without draining your primary reserves.
Rather than burning through your own liquid capital to fund a massive expenditure, you can use a loan to keep your cash working elsewhere. This strategy allows your existing money to stay tucked into high-yield vehicles. You are essentially using someone else’s money to maintain your investment momentum.
Then there is the matter of streamlining your liabilities. Many wealthy individuals find themselves juggling several different lines of credit or premium credit cards. Each one comes with its own unique interest rate and billing cycle, which can become a logistical headache.
By rolling these various obligations into a single, low-interest personal loan, you simplify your financial life. This consolidation makes your monthly cash flow much more predictable. More importantly, it slashes the total amount of interest you’ll end up paying to the banks over the long haul.
Navigating the Traps of Private Financing
Even for those sitting on a gold mine of income, small oversights can act like termites, slowly eating away at your accumulated net worth. Many borrowers fall into the trap of chasing a modest monthly bill while ignoring the mountain of debt hiding behind it. It is a classic case of missing the forest for the trees.
Take a $50,000 loan as a prime example. A mere 2% gap in interest rates might seem trivial on paper, but it can bleed thousands of dollars from your pocket over the term. Don’t get blinded by the monthly installment amount; instead, cast your eyes on the APR to find the real story.
The APR is your best friend in this scenario. Because it bundles the interest rate with any compulsory fees, it provides the most honest reflection of what your money actually costs. It is the true north of the lending world, guiding you away from deceptive, low-payment offers.
It is also vital to weigh how quickly you get your cash against the actual necessity of that speed. Sometimes, timing is everything in the world of high-stakes finance. If a golden opportunity lands on your desk, waiting a week could mean losing it forever.
Imagine a scenario where a business venture requires a 24-hour response time. In that moment, a 12% loan that lands in your account within sixty minutes is a much better tool than a 7% loan that sits in processing for ten days. Speed has a price, and sometimes, it is a price worth paying.
However, if your goal is simply to consolidate debt over several years, you should pivot your strategy entirely. In that case, hunt for the absolute lowest APR possible. When time is on your side, every fraction of a percent saved is a victory for your balance sheet.
Lastly, you must read the fine print to ensure you aren’t being handcuffed by prepayment penalties. Wealthy individuals often experience sudden surges in liquidity. You might find yourself wanting to wipe out a debt early to save on interest, but a sneaky fee can turn a bargain into a burden.
Before you put pen to paper, be incredibly direct with your lender. Ask them clearly, «Is there a penalty for paying this loan off in full within the first twelve months?» This isn’t just being cautious; it is being smart. For those with irregular, high-volume cash flows, having that exit door open is absolutely essential.

Top rated
-
 Cell phones
$250.00
-
sheath cell phone Samsung A20/ A30/ A50
$8.16
-
sheath cell phone Samsung A20s
$1.00
-
Samsung Bluetooth Headphones
$1.00
-
Xiaomi headphones
$10.00
Products
-
Cell phones
$250.00
-
Anker PowerCore portable charger
$39.99 – $55.99
-
Xiaomi headphones
$10.00
-
sheath cell phone Samsung A20/ A30/ A50
$8.16

