Get Loans for the Unemployed with Bad Credit: Best 6 Options Today
Last updated: 2026-10-16
Waking up to a sudden unemployment notice can feel like a punch to the solar plexus. It is a jarring transition that leaves you staring at a mounting pile of invoices that won’t wait for a new job. The anxiety of maintaining your home becomes a constant shadow when that reliable income stream dries up.
Life changes overnight, and it is rarely just about adjusting your coffee budget. It is about the fundamental necessity of survival in a fast-paced economy. Whether it is keeping the power running or ensuring the landlord gets their cut, the absence of a salary puts your entire foundation at risk.
Managing your current expenses while trying to salvage a future is a high-wire act. It requires a level of precision that most people never have to master. You find yourself performing a desperate dance, trying to stay above water today without completely draining your reserves for the weeks ahead.
The road gets significantly steeper if your credit report is riddled with scars. If your score is low, big-box banks will likely slam the door in your face. To many conventional institutions, a lack of steady work looks like a red flag for potential non-payment. Their algorithms are often programmed to reject these profiles instantly.
This can leave you feeling completely stranded in a digital wasteland of rejections. Automated systems do not have empathy for your circumstances; they only see numbers. This makes finding a lender who actually looks at the human being behind the data a significant challenge in today’s market.
We have curated a selection of companies that provide real pathways for those facing these specific hurdles during 2026. This overview focuses on providers that are willing to look past a damaged history or a temporary gap in employment.
- Avant
- Upgrade
- FastLendGo
- Wells Fargo
- NetCredit
- OneMain Financial
Our Selection Methodology
Navigating the world of lending requires peering through the smoke and mirrors of flashy marketing. When we analyzed these companies, we prioritized how quickly cash hits your pocket and how much flexibility the application offers. For those currently between roles, the ability to verify income through bank statements instead of pay stubs is a game-changer.
It truly is the difference between a successful application and a heartbreaking rejection. We dug deep into how lenders validate earnings via third-party data aggregators. This method acts as a vital safety net for freelancers or anyone with a fluctuating paycheck, shifting the focus from your employer to your actual ability to repay.
Honesty in pricing is another non-negotiable for our team. A lender might promise a quick fix, but predatory interest rates turn a temporary solution into a long-term nightmare. While a low monthly payment looks enticing, a 72-month term might force you to pay back double the original amount. We searched for that sweet spot between accessibility and fair terms.
| Lender Name | Loan Amounts | Terms/Rates | Funding Speed | Credit Requirements |
|---|---|---|---|---|
| Avant | See site | See site | See site | Bad Credit Options |
| Upgrade | Up to $50,000 | See site | Fast funding | See site |
| FastLendGo | $500 – $5,000+ | See site | Quick access | Bad/Fair/Good |
| Wells Fargo | See site | See site | See site | Traditional Requirements |
| NetCredit | Up to $10,000 | See site | Same-day available | Advanced Algorithms |
| OneMain Financial | $1,500 – $30,000 | From 11.99% APR | As soon as 1 hour | See site |
1. Avant
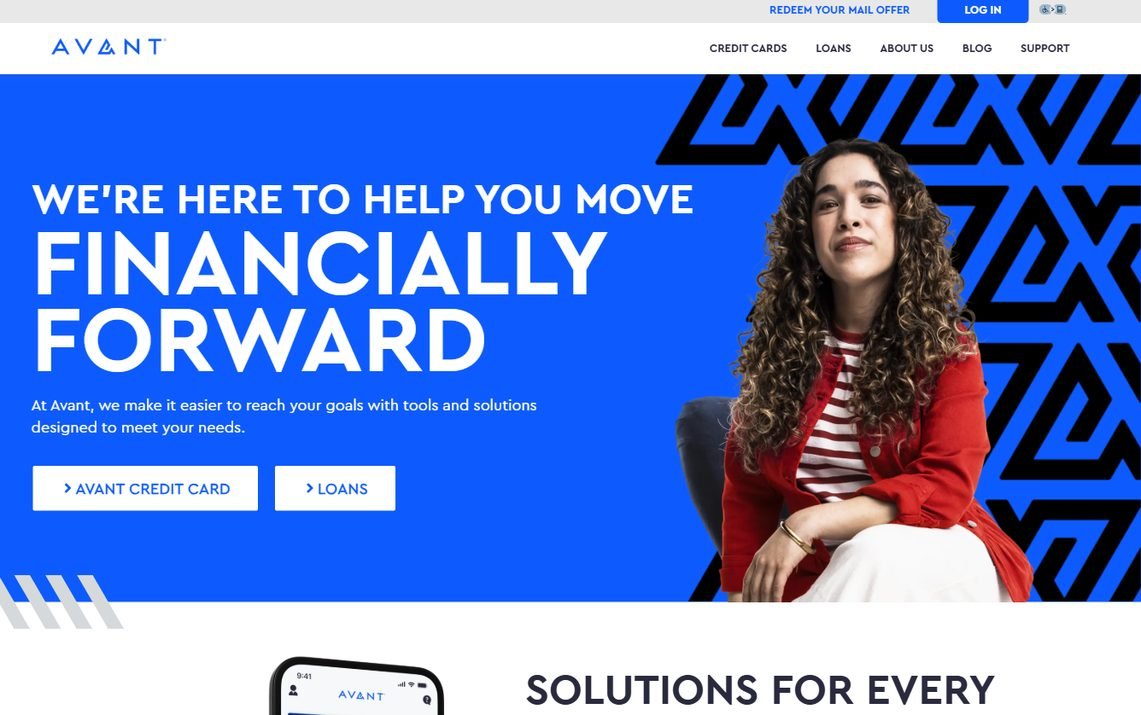
Life has a way of throwing curveballs, and Avant aims to help you navigate the chaos. They provide various financial tools, such as installment loans and credit cards, tailored for those seeking a fresh start. Unlike the rigid giants of the banking industry, they move away from strict FICO-only models to look at your broader financial health.
This makes them a sensible ally for debt consolidation or emergency expenses. If your car needs a sudden repair that might prevent you from attending interviews, or if you need to roll several debts into one single payment, they might be your best bet. They are an excellent resource for anyone managing irregular income streams.
Pros:
- Versatile loan solutions for various needs
- Provides credit card options alongside loans
- Focused on helping users achieve progress
- Publicly listed interest rates are not always available
2. Upgrade
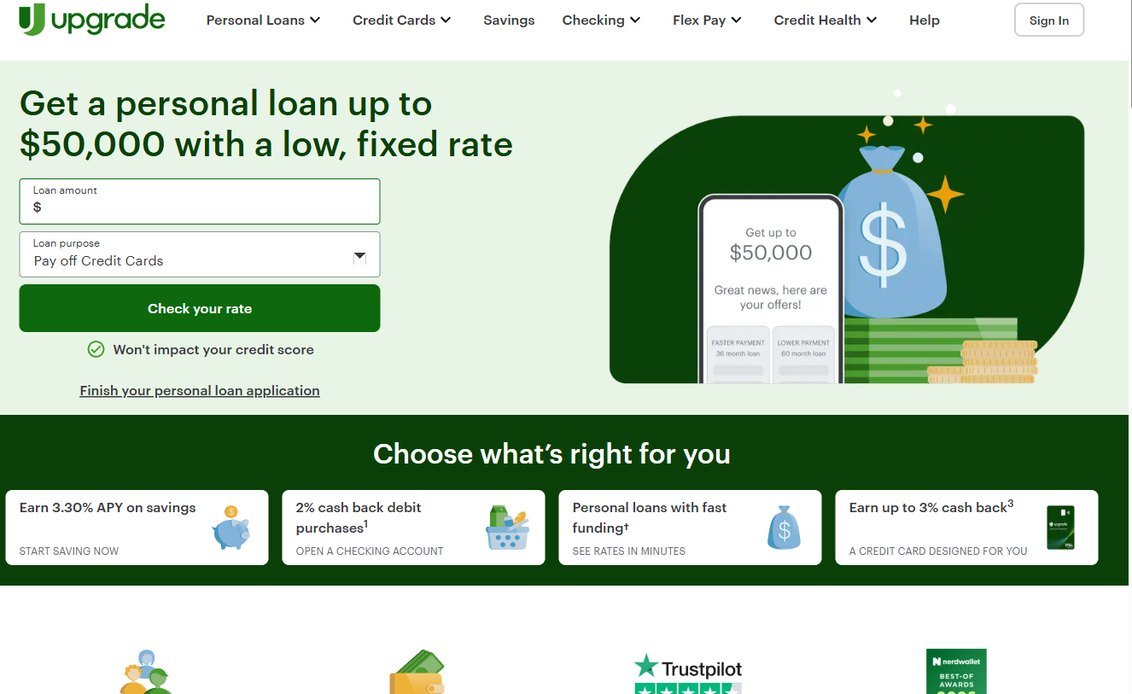
A heavyweight in the personal loan sector, Upgrade offers substantial capital, with limits reaching up to $50,000. Their funds can cover everything from major home upgrades to unexpected large purchases. Speed is their middle name; you can explore rates in mere minutes via a «soft pull» that won’t damage your score.
That «soft pull» is a total lifesaver when things get tight. It allows you to shop for the best deal without stacking up «hard inquiries» that drag your credit score down the drain. They also offer a checking account featuring debit purchase cash back, making them a handy financial hub.
If you require a significant sum to wipe out debts or kickstart a project, Upgrade’s streamlined process is hard to beat. Most of the heavy lifting happens right on your smartphone. It is a digital-first experience designed for the modern era, perfect for those without easy access to a physical bank.
Pros:
- Large loan limits up to $50,000
- Quick rate checks with zero credit impact
- Cash back perks via checking accounts
- Premium rates might require better credit
3. FastLendGo
When you need a quick infusion of cash to put out a fire, FastLendGo is a strong contender. They specialize in smaller personal loans, with minimums starting at just $500. This makes them ideal for covering immediate hurdles like utility deposits, dental work, or pressing auto repairs. (fastlendgo.com)
Simplicity is the name of the game here. The platform allows you to compare your options online with ease. Whether your credit status is good, fair, or bad, they maintain product tiers designed to fit your specific situation. A «fair» score backed by a history of steady income can often find better terms here than at a massive bank.
It is a highly accessible lifeline for someone in a pinch. They provide the immediate relief needed to stop a minor financial hiccup from turning into a full-blown crisis.
Pros:
- Low minimum loan threshold ($500)
- Addresses specific needs like dental or auto
- Easy online comparison of local rates
- Small loan focus may not work for large debts
4. Wells Fargo
Wells Fargo stands as a massive, storied institution. From home loans to basic checking accounts, they offer a complete spectrum of banking services. As a pillar of the American financial landscape, they provide a level of stability and physical presence that modern fintech apps simply cannot replicate.
However, if you are currently unemployed, you might find the climb here quite steep. Conventional banks usually demand two years of continuous employment documentation and a very stable debt-to-income ratio. They generally avoid taking risks on borrowers who lack a verifiable, steady paycheck.
That said, they are a fantastic destination for rebuilding your financial foundation once you secure new employment. If you are already a customer, it may be worth sitting down to discuss hardship assistance. Sometimes, a real conversation with a person can unlock doors that an algorithm keeps slammed shut.
Pros:
- A vast array of financial services
- Highly reputable and well-established
- Extensive wealth management offerings
- Stringent requirements for standard loans
5. NetCredit
NetCredit operates on the belief that you are much more than a single number on a screen. By utilizing advanced algorithms, they look beyond the standard FICO score. This is a lifeline for those with imperfect credit who still need significant financing. They can see reliability in your utility and rent payments that traditional reports miss.
With same-day funding options and loans reaching $10,000, they prioritize getting you your money quickly. Their application is straightforward, making them an attractive choice for consolidating high-interest credit card debt into one single, more manageable monthly payment.
Pros:
- Sophisticated underwriting via advanced algorithms
- Availability of same-day funding
- Loan amounts reach up to $10,000
- Subject to the rules of partner banks
6. OneMain Financial
If you find comfort in face-to-face interaction, OneMain Financial is a stellar choice. With roughly 1,300 branches nationwide, they are always around the corner. They provide personal loans ranging from $1,500 to $30,000, with rates beginning at 11.99% APR. Having a physical office to visit can provide immense peace of mind during stressful times.
Speed is a major selling point here, too. You can potentially see funds in your account as early as one hour after signing. This is perfect for urgent emergencies, like a broken furnace, where every passing hour feels like an eternity. Being able to explain your unique situation to a human loan officer offers a level of reassurance that a website simply can’t match.
Pros:
- Rapid funding (potentially in one hour)
- Large network of physical branches
- Fixed, predictable monthly payments
- Requires a formal loan signing process
Peering Behind the Financial Veil
Before putting pen to paper, you really need to grasp how APR differs from your scheduled monthly installments. The Annual Percentage Rate isn’t just a number; it bundles your interest rate alongside any required service charges. This metric serves as your primary compass for discovering the actual expense of your debt.
When life throws you a curveball, your eyes naturally gravitate toward the immediate monthly obligation. However, a tiny monthly bill can become a financial anchor if the repayment window stretches too far into the future. It is a dangerous game of smoke and mirrors.
Imagine a $500 monthly bill feels light enough to handle. If that obligation persists for sixty months, you are effectively paying back a mountain of cash far beyond your initial loan amount. It is a mirage of affordability that often pulls people into a bottomless pit of debt.
When weighing your various options, keep these three critical indicators close to your chest:
- The Full Price Tag: Take your monthly installment, multiply it by the total duration of the term, and toss in any initial costs. This figure represents the genuine amount you are handing over.
- Early Payoff Charges: Should you land a new role and want to crush your debt early, ensure there aren’t hidden fees for doing so. Always hunt for a «no prepayment penalty» guarantee in the fine print.
- The Cost of Setup: Some banks might skim a portion of your funds before they ever hit your bank account. If you ask for $1,000 but only receive $950, your real interest rate is much steeper than the advertised rate.
Navigating Your Way Back to Stability
Think of an emergency loan as a life jacket, not a luxury yacht. When you are currently out of work, use those borrowed funds strictly for survival. This means covering your rent, groceries, transit, and electricity. It is tempting to maintain your usual standard of living, but trying to look prosperous while broke is a recipe for disaster.
The primary objective here is simple: buy yourself the breathing room necessary to secure new employment. You want to bridge the gap without sinking into a pit of predatory interest rates. Every cent should serve a functional purpose during this transition period.
As you manage these tight finances, consider these practical maneuvers to safeguard your mental health and credit score:
- Reach Out to Lenders Early: If a car note or mortgage payment looks impossible, pick up the phone before the deadline passes. Most banks have specific programs designed for hardship or temporary forbearance to help people in your exact situation.
- Focus on the Essentials: When the wallet feels light, prioritize your «survival» costs. While your credit score is important, securing a roof over your head and food on your table must always come before paying off a credit card balance.
- Scrutinize Your Monthly Bills: It might seem trivial, but cutting that gym membership or a dozen streaming apps can save you $50 or $100 every single month. When you are living on a shoestring budget, those small victories aggregate into significant savings.
- Maintain Detailed Records: Create a physical or digital folder for every piece of correspondence from lenders. Keep all emails, loan terms, and applications organized. If a conflict arises down the road, a solid paper trail will be your strongest ally.
During a career gap, every single penny carries immense weight. A single misstep can become a very costly blunder. Before signing anything, dive deep into the fine print. You need to understand the total cost of borrowing the money, not just the monthly installment amount. You do not want to find yourself shackled by high interest when things are already difficult.
Avoid the temptation to grab multiple small loans from various lenders all at once. This is a fast track to a debt spiral that is incredibly hard to break. Instead, hunt for a single, cohesive solution that solves your most pressing problem and offers a repayment schedule that actually works with your current cash flow.
If the walls feel like they are closing in, remember that high-interest loans aren’t your only option. Sometimes, negotiating directly with your existing creditors or seeking out local community assistance offers much more relief than adding new debt to your plate. Always balance the immediate need for cash against the long-term damage a loan might cause.

Top rated
-
 Cell phones
$250.00
-
sheath cell phone Samsung A20/ A30/ A50
$8.16
-
sheath cell phone Samsung A20s
$1.00
-
Samsung Bluetooth Headphones
$1.00
-
Xiaomi headphones
$10.00
Products
-
Cell phones
$250.00
-
Anker PowerCore portable charger
$39.99 – $55.99
-
Xiaomi headphones
$10.00
-
sheath cell phone Samsung A20/ A30/ A50
$8.16

