Where to Secure First Time Personal Loans No Credit History Today
Last updated: 2026-10-16
Attempting to secure a loan from a traditional bank without a documented credit trail is like wandering through a dense fog without a compass. If your history lacks auto loans or credit card usage, mainstream institutions might treat your application like it doesn’t exist. It is a maddening loop where proving your reliability requires the very credit history you lack.
This financial paradox keeps many individuals stuck in a state of uncertainty. Newcomers to the country, fresh graduates, and those rebuilding after a rough patch frequently find themselves shut out of essential economic tools. It often feels as though the entire banking structure is intentionally built to keep you on the periphery.
Thankfully, the landscape of lending has undergone a massive transformation this year. Modern lenders are no longer obsessed with a solitary FICO score when evaluating your potential. They have shifted their gaze toward your real-world earnings, the stability of your current employment, and your daily fiscal behaviors.
In fact, your record of paying rent and keeping up with utility bills holds significantly more leverage now than it did half a decade ago. By evaluating your complete financial portrait instead of a single digit, companies can now approve millions of people who were once deemed ungradable.
This pivot toward diverse data sets means your steady paycheck and timely monthly payments are your greatest assets. For anyone standing on the threshold of their first loan, these consistent habits are the keys to unlocking new doors.
- JetzLoan
- Discover
- OppLoans
- OneMain Financial
- Coastline Credit Union
Our Criteria for Selecting Top Lenders for First-Time Borrowers
While compiling this list, our primary objective was pinpointing financial institutions that welcome individuals lacking a traditional credit history. We hunted for providers that facilitate «soft pulls» or preliminary pre-qualification procedures. Understanding this nuance is everything.
A soft inquiry functions like window shopping; it allows you to browse interest rates without hurting your FICO standing. It is a risk-free way to scout your options before committing to any formal application process.
Conversely, a «hard inquiry» carries more weight. This occurs when a company thoroughly examines your financial records to finalize an agreement, which can cause your score to drop. We prioritized firms that utilize soft checks early on to shield your developing credit profile from accidental harm.
Speed and clarity were our subsequent pillars of evaluation. If a company buries extra costs in the legal jargon or takes a fortnight to transfer funds, they fail the test of utility. When a sudden medical expense or a broken car transmission hits, you need liquid capital, not delays.
We vetted organizations to ensure they offer rapid disbursement, upfront cost disclosures, and accessible customer service agents. You shouldn’t have to hunt for a human being just to get a simple answer about your money.
Transparency regarding the APR was also a non-negotiable requirement. This figure serves as the ultimate reality check because it merges the base interest rate with all compulsory service fees. By examining the APR, you grasp the true long-term price of your borrowing.
We also scrutinized whether a loan functions as a stepping stone for financial health or a bottomless pit of debt. We leaned toward lenders featuring stable, predictable monthly installments. Steer clear of entities utilizing predatory math that triggers a cycle of endless owing.
Our team analyzed the distinction between compounding interest and simple interest. Because the latter is much more manageable, we stayed away from models where interest on interest causes your total balance to skyrocket unexpectedly.
| Provider | Available Funding | Transfer Time | Credit Score Risk | Loan Duration |
|---|---|---|---|---|
| JetzLoan | $500 – $35,000 | Within 24 hours | No hard credit pull | see site |
| Discover | $2,500 – $40,000 | Next business day | No impact to credit score | see site |
| OppLoans | see site | Same-day funding available | Does not affect FICO score | see site |
| OneMain Financial | $1,500 – $30,000 | 1 hour after signing | No credit score impact | 24-60 months |
| Coastline Credit Union | see site | see site | see site | see site |
Our Top Picks for 2026 Lenders
1. JetzLoan
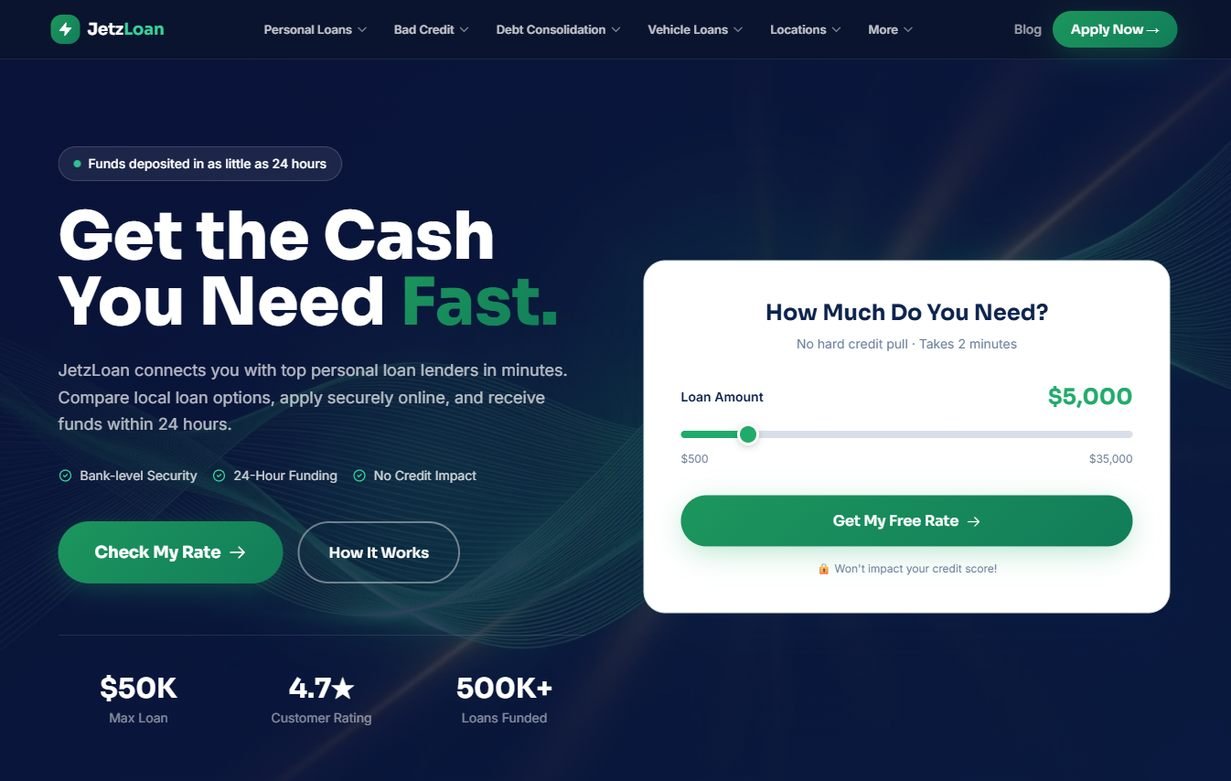
Navigating the choppy waters of a limited credit history can feel overwhelming. JetzLoan acts as your personal guide, bridging the gap between you and a variety of premier lending institutions. It serves as an excellent resource if you suddenly need funds for an urgent car repair or to manage pressing debts.
Rather than hunting through dozens of websites and risking your score with multiple hard inquiries, JetzLoan simplifies the entire ordeal. They consolidate your potential choices into a single, streamlined process. This approach protects your financial standing while you explore different possibilities.
The process is lightning-fast, typically wrapping up in a mere two minutes. Because they utilize a soft inquiry method during the initial phase, you can browse options without any anxiety. You may even discover you qualify for as much as $35,000. This is a wonderful safety net for those just starting their borrowing journey and wanting to learn the ropes without damaging their credit.
Pros:- Funds delivered within 24 hours
- Maximum amounts reaching $35,000
- Quick two-minute application process
- Checking availability won’t hurt your score
- Requires an initial simple form
2. Discover
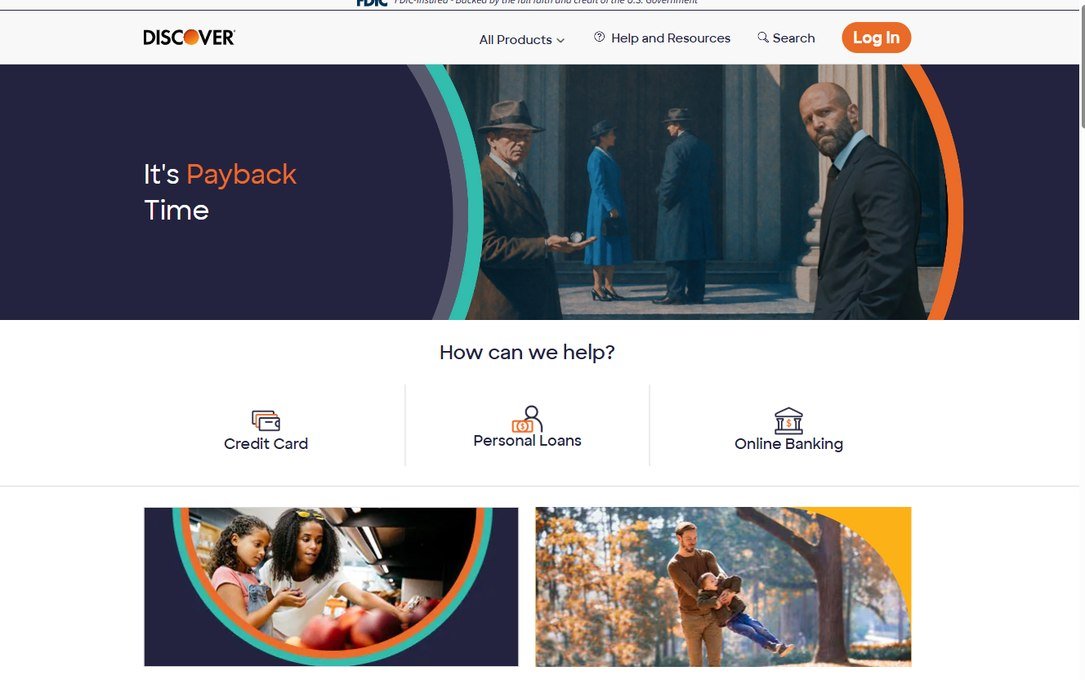
When it comes to banking giants, Discover stands tall, offering the kind of institutional stability that brings peace of mind. Their personal loans are crafted for individuals seeking a long-term financial ally rather than just a temporary fix. With interest rates beginning at 6.99% APR, they provide a genuine ladder for financial growth.
As you transition from having no credit to building a solid profile, Discover provides a structured framework that rewards consistent, on-time payments. Their pre-approval system is incredibly transparent and won’t impact your credit rating. Once you receive the green light, the capital could arrive in your bank account by the very next business day.
For those with a regular paycheck looking to partner with a major entity, this is a stellar choice. Their digital infrastructure is top-notch, allowing you to handle everything from mobile payments to statement reviews through a highly intuitive app. It makes managing your financial health feel like a walk in the park.
Pros:- Loan ceilings reaching up to $40,000
- Rates as low as 6.99% APR
- Next-day funding capability
- Reputable, FDIC-insured institution
- Income thresholds might be more stringent
3. OppLoans
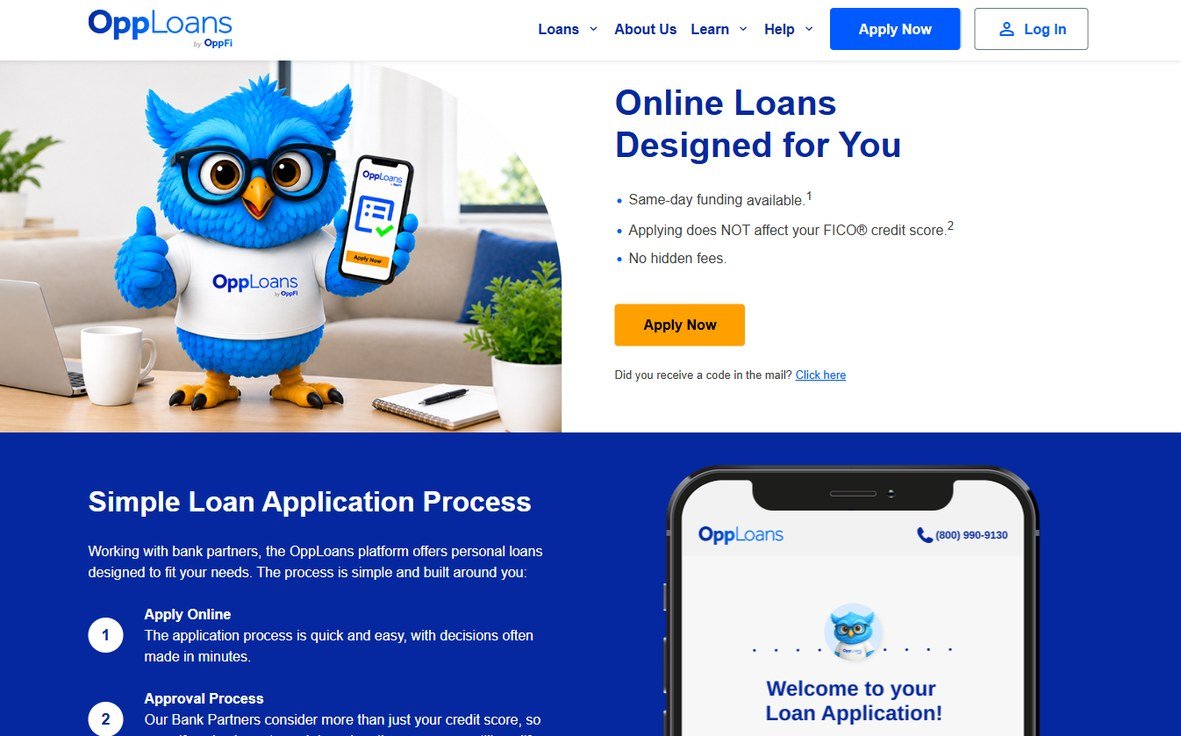
OppLoans is the perfect alternative for anyone who has encountered a «no» from traditional big-box banks. Instead of obsessing over a single FICO score, they look at the bigger picture of your financial life. This makes them a lifeline for people facing unexpected hurdles, such as a sudden medical bill or a temporary lapse in employment.
They prioritize your current cash flow, often evaluating your recent banking activity over a static bureau number. The platform is built for speed, offering the possibility of same-day funding. It serves as a much safer harbor than the high-risk payday loan market.
While payday loans can be a debt trap due to interest rates soaring above 400% APR, OppLoans offers a much more sustainable path. You can tackle your immediate needs without falling prey to the predatory terms and hidden costs that make other quick-cash avenues so dangerous for the average consumer.
Pros:- Possibility of same-day cash access
- Zero impact on your FICO score
- Tailored for those denied by big banks
- No hidden fees lurking in the fine print
- Rates may exceed those of traditional lenders
4. OneMain Financial
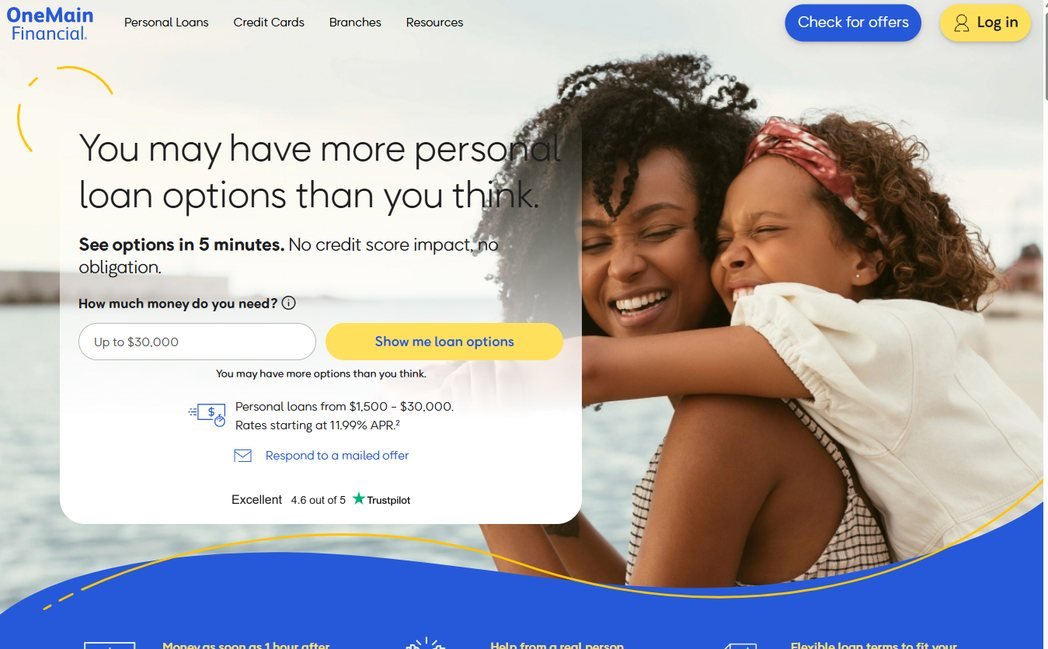
OneMain Financial strikes a perfect balance between modern digital convenience and the comfort of human interaction. With a massive network of 1,300 physical branches, you aren’t limited to talking to a computer screen. This is incredibly helpful if you need to sit down with a representative to explain a specific life change, like a fluctuating income.
That personal connection can often be the deciding factor in whether your application gets the thumbs up or the thumbs down. They provide flexible repayment windows ranging from 24 to 60 months, allowing you to customize your monthly obligation. With minimum loans starting at $1,500, they cover everything from minor home repairs to large-scale debt consolidation.
The turnaround time is nothing short of impressive. In some cases, you might have access to your money just sixty minutes after the paperwork is finalized. It is a rare find to see such rapid service from a lender with such a massive physical footprint across the country.
Pros:- Large branch network for face-to-face support
- Rapid funding (one hour after signing)
- Repayment terms up to 60 months
- No-obligation pre-check options
- Interest rates can fluctuate significantly
5. Coastline Credit Union
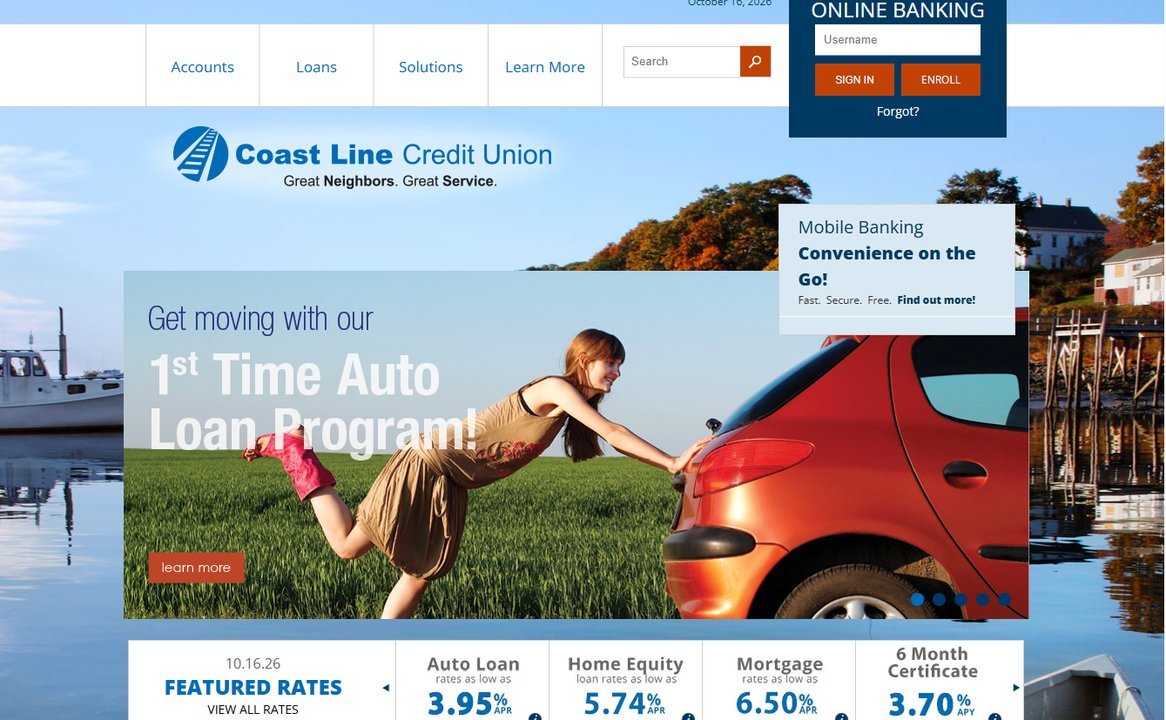
For many new borrowers, credit unions are the industry’s best-kept secret. Coastline Credit Union operates on a member-centric philosophy, which usually translates to a much more personalized experience. Unlike massive banks driven by shareholder profits, credit unions function as cooperatives that exist to serve their members.
Because their mission is to support the local community, their lending criteria can be more accommodating to local residents. You may need to meet specific membership requirements, such as residing in a certain county or working in a particular industry, but the benefits are often well worth the effort. They provide a suite of digital tools and diverse loan products to assist your journey.
Think of this as a «slow and steady» approach to building a sturdy financial foundation. The lender is truly rooting for your long-term prosperity, rather than simply trying to extract as much interest from you as possible in a single month.
Pros:- Focus on member-driven service
- Wide array of financial products
- Potential for superior long-term rates
- Membership eligibility may be restricted
Decoding the Cost: The Gap Between APR and Simple Interest
Navigating the sea of loan advertisements can feel like trying to read a map in a storm. You will inevitably encounter two distinct figures that seem to be shouting for your attention. If you aren’t careful, you might find yourself paying much more than you originally anticipated.
The first figure is the Simple Interest Rate. Think of this as the base price tag for the money you are renting. It represents only the fundamental cost of borrowing your principal amount, but it leaves out several crucial details.
This number is essentially a half-truth that can lead you astray. It tells you the rate applied to your balance, yet it fails to account for the «hidden» extras that sneak into your monthly budget. It’s the tip of the iceberg.
The Annual Percentage Rate (APR) is the real heavyweight you need to watch. Unlike simple interest, the APR offers a transparent view of the total cost. It bundles the interest rate together with mandatory extras, such as documentation or origination fees.
If you want to protect your bank account, the APR is your best friend. It provides the most accurate reflection of what a loan will truly cost you over the course of a year. It is the gold standard for comparison.
Let’s look at a real-world scenario to clear the fog. Imagine you secure a $5,000 loan with a 10% interest rate. However, the bank hits you with a $500 «processing fee» upfront. Suddenly, your APR is significantly higher than that initial 10% figure.
Always use the APR as your primary tool when shopping around. Suppose Lender A offers a 7% rate but piles on heavy fees. Meanwhile, Lender B offers an 8% rate with absolutely no extra charges. In this case, Lender B is the winner.
It might seem counterintuitive at first, but the lower rate isn’t always the better deal. Do not let a flashy, low «headline» interest rate pull you into a bad contract. Always look past the surface to see the full price tag.
Essential Guidelines for Your First Loan
Stepping into the world of credit can feel like walking a tightrope without a net. To keep your feet firmly on solid ground, you should always adhere to a few fundamental principles. These simple strategies act as a safety harness, ensuring you don’t lose your grip on your long-term financial stability.
Think of your budget as a delicate ecosystem that needs balance to survive. If you overload it with too many obligations, the whole system might collapse. Following these steps will help you navigate the murky waters of debt without drowning in unexpected interest or heavy monthly burdens.
Consider this a roadmap for your journey through the lending landscape. While the allure of easy cash is strong, the hidden costs can bite hard if you aren’t paying attention. Keep these three pillars in mind to ensure your borrowing experience remains a tool for growth rather than a trap.
- The 30% Ceiling for Monthly Obligations: Never allow your recurring debt installments to swallow more than 30% of your net income. For instance, if your monthly take-home pay totals $3,000, your combined debt payments should remain significantly under that threshold. If a lender demands half your paycheck just to cover interest and principal, you are dancing dangerously close to the edge of default.
- Resist the Urge to Stretch Terms: It is incredibly easy to fall for a 60-month repayment plan just because the individual monthly installments seem more manageable than a 36-month option. However, time is a very expensive commodity in the lending world. By extending the duration of your loan, you end up paying a staggering amount in extra interest. Over a 60-month period, you might find yourself returning nearly twice the original principal. If your wallet allows, always opt for the shorter duration to save money in the long run.
- Scrutinize the «Complete Repayment Amount»: Before putting pen to paper, you must ask a vital question: «What is the absolute sum I will have surrendered by the final payment?» This figure represents the cold, hard truth of the deal. If you take out a $2,000 loan but the total repayment reaches $3,500, you have effectively paid a $1,500 fee to access that cash. Understanding this metric prevents the inevitable stomach-drop when you review your bank statements down the road.
Strategies for Your Initial Loan Request
Before you press that final submission button, you need a roadmap. Taking out a loan isn’t just a quick fix for a cash crunch; it is a solemn promise to follow a strict repayment timeline. You should determine your exact financial requirement to prevent over-borrowing. It is far less stressful to retire a minor debt than to struggle under a mountain of principal.
Many borrowers fall into the trap of requesting the highest possible limit just to create a «safety net.» Unfortunately, this mistake forces you to pay interest on funds that sit idle in your bank account. Instead, aim for precision. Knowing exactly what you need keeps your interest costs down and your financial peace of mind high.
Don’t get blinded by a tiny monthly installment. While a small payment looks attractive, you must scrutinize the APR and the cumulative cost over the entire duration of the loan. A deceptive, low monthly figure often signals an extended timeline. This can end up costing you thousands of extra dollars in interest charges over the years.
Grab a digital calculator and play with the numbers. You might find that increasing your monthly contribution by a mere $25 can shave hundreds of dollars off your total debt. Seeing these numbers in black and white makes the long-term benefits of aggressive repayment crystal clear.
Get all your paperwork in a pile before you dive in. Even if a lender claims a hard credit check isn’t required, you will eventually have to verify your identity and earnings to finalize everything. Keeping your recent pay stubs, bank records, and ID close at hand will prevent last-minute headaches during the process.
If your goal is to consolidate existing debt, make sure you have those specific creditor statements ready. Some lenders offer the convenience of paying your old debts directly. This shortcut can make the entire transition feel like a breeze rather than a bureaucratic nightmare.

Top rated
-
 Cell phones
$250.00
-
sheath cell phone Samsung A20/ A30/ A50
$8.16
-
sheath cell phone Samsung A20s
$1.00
-
Samsung Bluetooth Headphones
$1.00
-
Xiaomi headphones
$10.00
Products
-
Cell phones
$250.00
-
Anker PowerCore portable charger
$39.99 – $55.99
-
Xiaomi headphones
$10.00
-
sheath cell phone Samsung A20/ A30/ A50
$8.16

