Top Rated Lenders for a Personal Loan with Co signer Today
Last updated: 2026-10-17
Navigating the lending landscape with a subpar credit score often feels like wandering blindly through a heavy mist. You might feel stuck, staring at a closed door when your finances aren’t quite where they need to be. Many borrowers seek a lifeline by asking a family member or a trusted buddy to join the application.
This person acts as a co-signer, essentially lending their stellar reputation to help you cross the finish line. It is a massive gesture of faith that can turn a «no» into a «yes.» Suddenly, that elusive capital for an unexpected hospital visit or a broken-down vehicle becomes a reality instead of a dream.
Don’t just get swept up in the allure of a small monthly installment. It is easy to fall into a trap if you ignore the fine print hidden in the shadows. You must evaluate the entire lifecycle of the debt, not just the immediate relief it provides to your wallet.
A tiny monthly bill might seem like a blessing, but if the repayment window hits 72 months, the interest will bleed you dry. Similarly, a company boasting instant money might be packing its terms with predatory origination fees. Always check if the speed of funding comes at a staggering premium compared to standard banking institutions.
- FastLendGo
- OneMain Financial
- Upgrade
- Together Loans
- U.S. Bank
- MoneyLion
- MedLoan Finance
Our Methodology for Ranking Top Lenders
Our team dove deep into the current marketplace to find the best options for borrowers bringing on a co-signer. We wanted to see how these institutions react when a single application involves two separate individuals. It was vital to determine if the rules for the second party were laid out plainly or hidden behind a mountain of legal jargon.
We scrutinized whether firms demanded a full joint application or offered a simpler guarantor role instead. This distinction is the difference between a light breeze and a category five storm for the person signing on. We prioritized companies that streamlined the whole ordeal rather than those that piled more red tape onto your plate.
Honesty served as our North Star throughout this investigation. We hunted for providers that offer rapid decisions, upfront interest costs, and a wide range of loan sizes. We also measured the «friction» of each digital journey. This involved checking how many files you must upload, how easily signatures are handled online, and the clarity of the Annual Percentage Rate (APR) descriptions.
| Financial Provider | Available Funding | Interest & Terms | Speed of Payout | Credit Profile |
|---|---|---|---|---|
| FastLendGo | $500 – $5,000+ | visit website | visit website | Poor to Excellent Credit |
| OneMain Financial | $1,500 – $30,000 | Starting at 11.99% APR | Within 60 minutes | Helpful for Low Credit |
| Upgrade | As much as $50,000 | Fixed-rate options | Quick disbursement | Focus on Credit Health |
| Together Loans | Up to $10,000 | 6 to 20 years (24 – 60 months) | Approval within 24 hours | Bad Credit Specialists |
| U.S. Bank | visit website | visit website | visit website | Standard Banking Services |
| MoneyLion | Up to $100,000 | visit website | Expedited options available | Focus on Credit Building |
| MedLoan Finance | $500 – $100,000 | 12-18 Months Interest Free | visit website | Specialized Medical Loans |
Premier Co-signer Loan Providers for 2026
1. FastLendGo
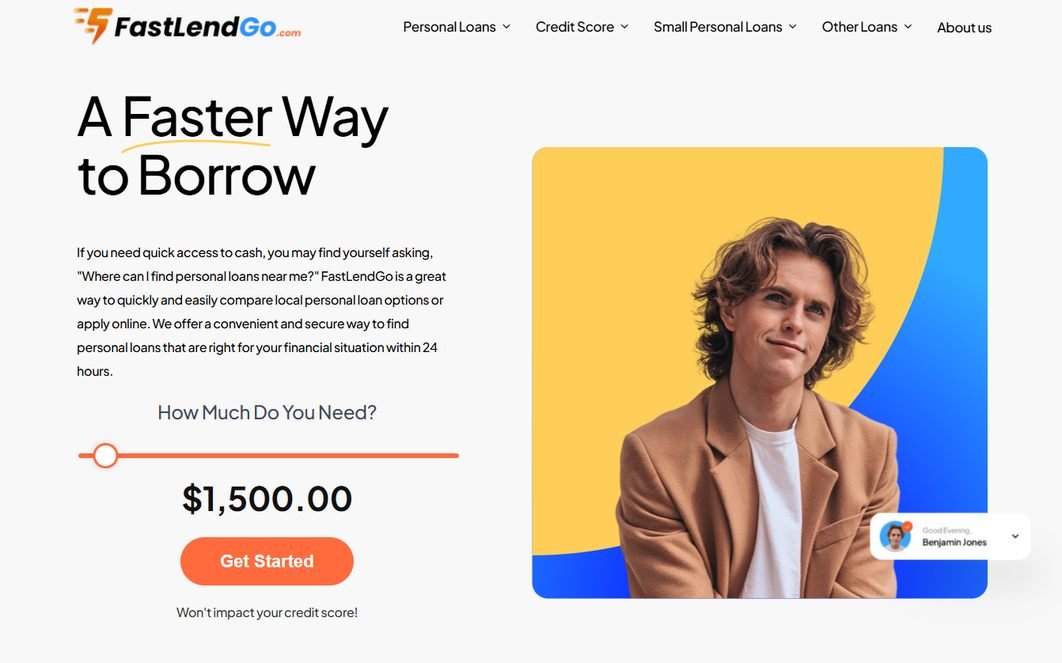
Life throws curveballs, and FastLendGo is there to catch them without making you jump through endless hoops. Whether you are facing a $500 emergency or planning a massive life transition, they have you covered. They cater to various needs, providing a lifeline for those who need cash quickly.
Their approach is far more relaxed than a traditional mortgage department. This flexibility makes them an ideal choice for gig workers or anyone whose income fluctuates month to month. If you use fastlendgo.com, you might find the process quite smooth.
For those with a «thin» credit history, this lender can be a true lifesaver. Standard algorithms often miss the mark when they can’t find much data on your past borrowing. Because they offer specialized paths for high earners and those with poor credit, a co-signer can help bridge the gap in your financial story.
Pros:
- Starting amounts from $500 make small emergencies manageable.
- Funds can cover specific needs like car repairs or dental work.
- A variety of options exist for different credit profiles.
Cons:
- Their niche focus means they might not suit general debt consolidation.
2. OneMain Financial
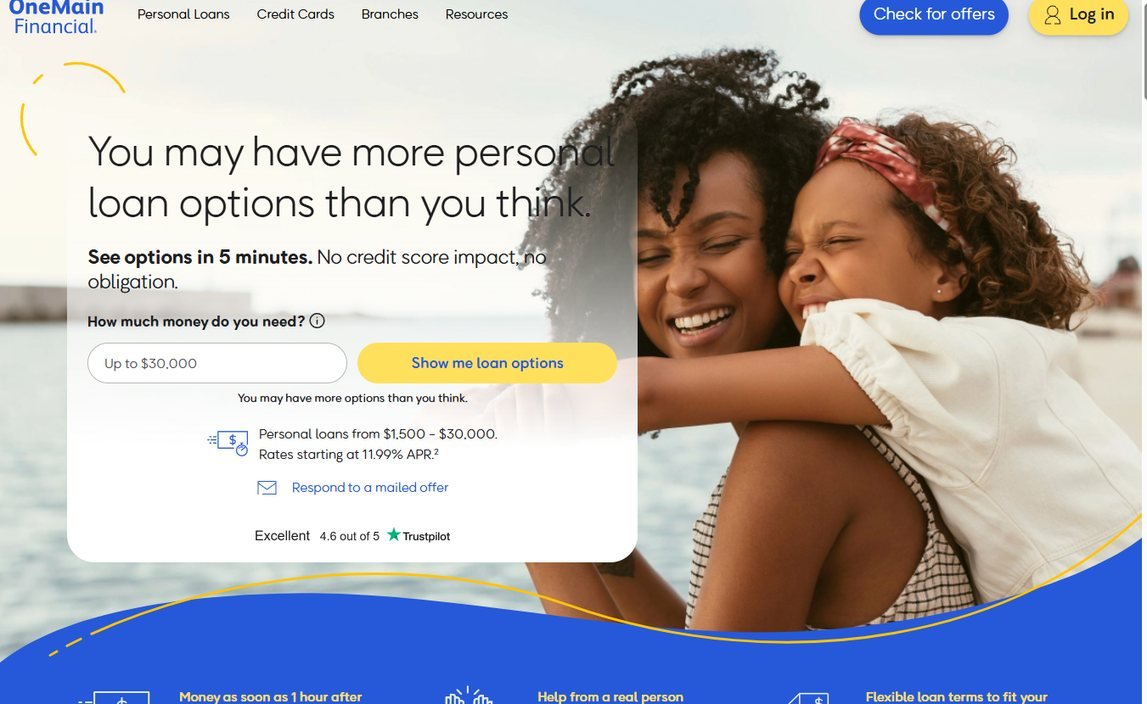
Sometimes, you just want to look a human being in the eye instead of battling a smartphone app. With a massive network of over 1,300 physical branches, OneMain Financial offers a level of accessibility that digital-only lenders simply cannot replicate. It is a comforting feeling to sit in a real office.
If you are nervous about explaining your financial quirks to a computer, their loan officers can provide much-needed peace of mind. They are built for speed, meaning you could potentially access your funds just one hour after the paperwork is signed. It is efficient and straightforward.
Their joint loan setups are incredibly user-friendly, making it easy for families or couples to share the burden. This simplifies the entire process of bringing a co-signer into the fold. It takes the guesswork out of your financial commitments.
Pros:
- Rapid funding is available, sometimes within a single hour.
- Extensive branch coverage provides easy access to in-person support.
- Joint loans from $1,500 to $30,000 simplify the co-signer experience.
Cons:
- Low credit scores may lead to higher interest rates over time.
3. Upgrade
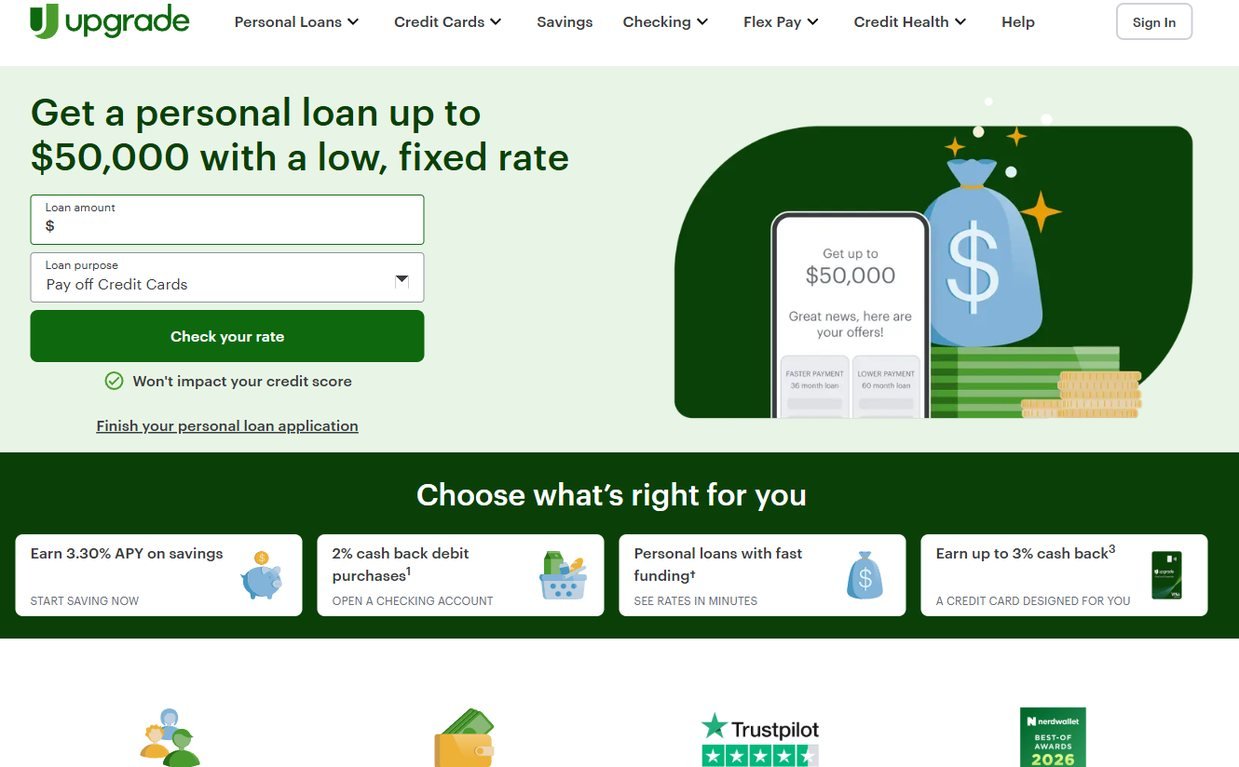
Upgrade takes a modern, holistic look at your long-term financial health. They aren’t just about loans; they act as a one-stop shop with everything from savings accounts to credit cards. Their website is incredibly intuitive, allowing you to explore different repayment scenarios before committing.
Whether you are tackling debt or funding a large purchase, the application process is remarkably smooth. A standout feature is their «soft pull» credit check. This allows you to scout rates and APRs without causing any damage to your credit score.
It is a great way to shop around without any penalty. By seeing your estimated payments upfront, you can make an informed decision without the usual anxiety associated with credit inquiries.
Pros:
- Inquire about rates without hurting your credit score.
- Funds can be used for various needs, including debt or home repairs.
- Certain products even offer the benefit of cash back rewards.
Cons:
- The breadth of products might feel overwhelming if you want something simple.
4. Together Loans
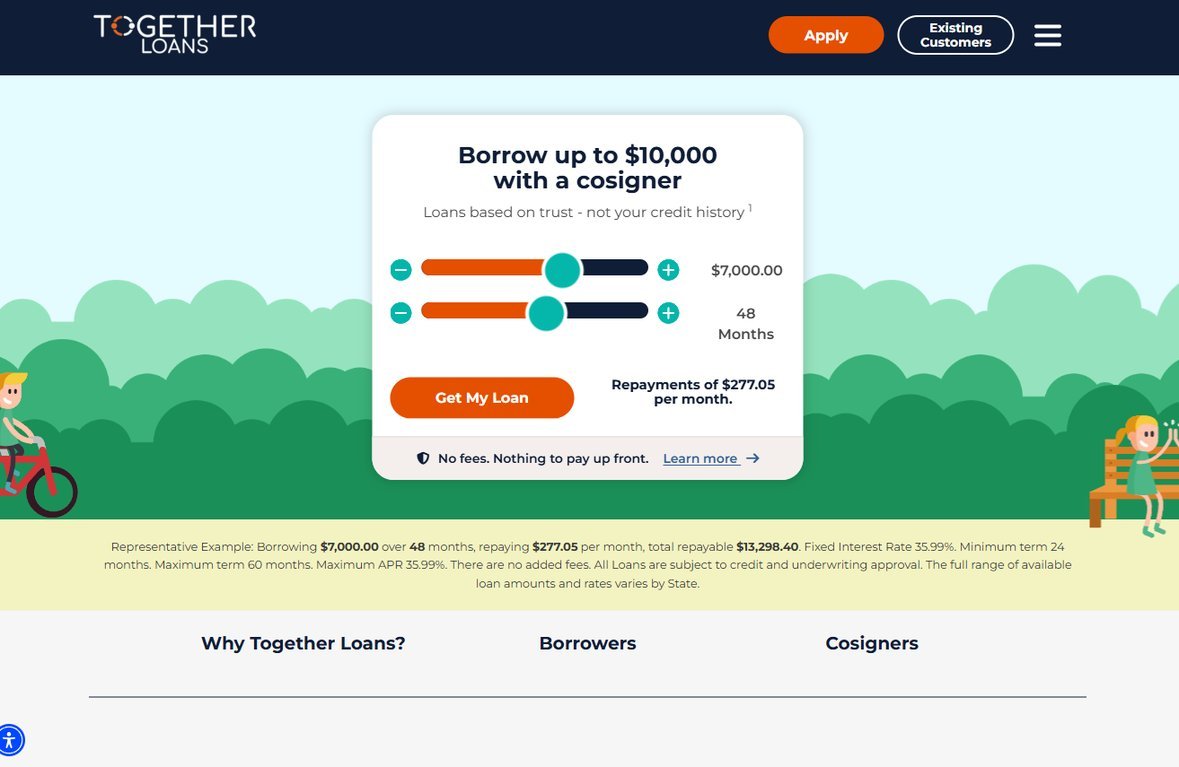
Together Loans operates on a philosophy of trust, looking beyond mere digital scores. This approach is a massive boon for individuals with a strong co-signer but a rocky credit history. Life is unpredictable, and a single setback shouldn’t define your entire financial future.
They understand that things like medical bills or job losses can temporarily tank a score. By looking at the human story behind the numbers, they offer loans up to $10,000 with lightning-fast approvals. You can often hear back within 24 hours.
If an unexpected bill lands on your desk, this is a reliable option. Adding a co-signer here can unlock much more favorable terms than you could ever secure on your own. It’s about finding a partner in your financial journey.
Pros:
- Focuses on personal circumstances rather than just rigid algorithms.
- Quick 24-hour approval is ideal for urgent financial needs.
- No upfront fees ensure you receive the full requested amount.
Cons:
- Be sure to check the fine print as interest rates can be higher.
5. U.S. Bank
If you crave the stability of a massive, long-standing institution, U.S. Bank is a rock-solid choice. They are particularly efficient if you are already a customer. An existing relationship means they already understand your cash flow, which can speed up verification.
While they might not match the breakneck speed of a new fintech startup, their infrastructure is enormous. They offer a complete suite of services, from simple checking to complex wealth management. It is a comprehensive ecosystem for your money.
If you are saving for a wedding or a major life milestone, the sheer scale of a big bank provides a sense of security. You can rest easy knowing you are dealing with an established giant.
Pros:
- Provides high levels of stability and consumer protection.
- A wide array of financial services available in one place.
- Seamless management for existing banking customers.
Cons:
- Personal loan requirements may be more stringent than niche lenders.
6. MoneyLion
MoneyLion is designed for the smartphone generation. Their app acts more like a personal financial assistant than a simple lending tool, helping you manage daily spending while simultaneously building your credit. It is all right there in your pocket.
With loan limits reaching up to $100,000, they are equipped to handle significant life changes like funding an education. Because they prioritize credit building, they are an excellent partner for anyone aiming to eventually move away from needing a co-signer.
The ultimate goal is independence. They provide the tools to help you eventually stand on your own two feet without needing external support.
Pros:
- Very high loan limits available for major life projects.
- In-app tools provide valuable credit education.
- The mobile user interface is incredibly easy to use.
Cons:
- Some rapid cash features may incur additional fees.
7. MedLoan Finance
MedLoan Finance has one specific mission: tackling medical debt. If you are facing costs for LASIK, dental procedures, or major surgeries, they provide specialized funding. They understand the unique timing and nature of healthcare expenses in a way general lenders often miss.
They offer various loan amounts and even provide interest-free windows for certain timeframes. If a surgery is on your calendar, using a medical specialist can be far more cost-effective than a standard high-interest personal loan.
It is a targeted solution for a very specific problem. By aligning with medical costs, they help you manage your health and your finances simultaneously without unnecessary stress.
Pros:
- Specialized expertise in dental and elective medical procedures.
- Interest-free options for 12-18 months can save significant money.
- Can cover large medical expenses reaching $100,000.
Cons:
- Funds are strictly limited to medical-related expenses.
The Weight of Responsibility for Your Co-signer
Taking on the role of a co-signer is a massive commitment that carries significant legal weight. It isn’t merely a gesture of support or a nod of approval toward your character. When they put their signature on that contract, they are essentially stepping into your shoes regarding the financial obligation.
Should you fall behind on your installments, the bank won’t hesitate to pivot their focus toward them. They become the primary target for the total sum owed, which encompasses all accrued interest and any penalty fees. It is a heavy mantle to hand to a loved one.
The fallout can be quite brutal if things go south. We are talking about potential legal battles or even the direct seizure of their wages to settle the debt. Beyond the courtroom, the damage to their credit rating can be swift and devastatingly permanent.
Their credit history will reflect this entire loan, regardless of how disciplined you might be with your payments. Even if you are perfectly punctual, that large balance remains a looming shadow on their profile. It can act as a massive anchor, pulling down their ability to borrow elsewhere.
Imagine them trying to secure a mortgage for a new home or financing a reliable vehicle next year. Lenders will scrutinize that existing debt, fearing it might compromise their ability to handle new monthly obligations. It is a high-stakes gamble that could jeopardize their future financial freedom.
How to Prepare for a Co-signer Application
If you want the best chance of getting approved, you need to be prepared. This means more than just having your ID ready; you need a rock-solid plan for how you will pay the money back. We suggest taking these steps before you even start the application:
- Make a Payment Plan: Map out exactly when and how you will pay. Leave some extra room in your budget for months when things might get tight.
- Check the Co-signer’s Credit: Most lenders want your co-signer to have a score between 670 and 700. If their score is low, you might be wasting your time.
- Get Your Papers Ready: Lenders will want to see pay stubs, W-2s, and proof of where you live. Having these in a folder can save you days of waiting.
- Read the Contract Together: Don’t just sign the papers. Sit down with your co-signer and read the part about what happens if you miss a payment.
Navigating the Co-signer Process
Before you ask anyone to co-sign, you need to have a very honest conversation. They need to know that they are legally responsible for the money. If you have a falling out or if you lose your job, their credit score will take the hit just as much as yours. Money has a way of straining even the strongest family ties.
Don’t assume a co-signer is just a formality. Lenders treat them as a primary guarantor. If your co-signer’s credit isn’t much better than yours, the lender might still say no or give you a much higher interest rate. In that case, the co-signer isn’t actually helping you save money.
Finally, don’t borrow more than you actually need just because you can. Interest adds up fast, and the total cost can become a massive number over time. Use a co-signer to get a better deal, not just to borrow more money than you can handle.

Top rated
-
 Cell phones
$250.00
-
sheath cell phone Samsung A20/ A30/ A50
$8.16
-
sheath cell phone Samsung A20s
$1.00
-
Samsung Bluetooth Headphones
$1.00
-
Xiaomi headphones
$10.00
Products
-
Cell phones
$250.00
-
Anker PowerCore portable charger
$39.99 – $55.99
-
Xiaomi headphones
$10.00
-
sheath cell phone Samsung A20/ A30/ A50
$8.16

