Best Rates for Bad Credit Loans California: Get Approved Fast Online
Last updated: 2026-10-16
Navigating the financial landscape in California can feel like wandering through a dense mist, especially when your credit rating isn’t quite where it needs to be. Life doesn’t wait for a perfect score, and many people find themselves scrambling to bridge the gap during unexpected emergencies.
Whether you are staring down a sudden transmission failure in Los Angeles or a surprise medical deductible in San Diego, financial hiccups arrive without knocking first. You might need to cover urgent car repairs or unexpected medical bills without being instantly rejected by major traditional banks.
Finding a reliable lender requires looking past the shiny commercials to scrutinize the fine print, the speed of funding, and those pesky interest rates. It is incredibly easy to get seduced by «low monthly payment» promises that actually hide the true cost of your borrowed money.
In reality, your total debt load is dictated by the length of the loan term and the Annual Percentage Rate (APR). We have put together this list to highlight the best options for Californians seeking flexibility and a legitimate chance at approval, even with a bumpy financial past.
- OneMain Financial
- Avant
- FastLoans CA
- Upgrade
- VivaLoan
- GreendayOnline
- United Finance
How We Vetted California Borrowing Options
Finding a reliable lender feels like searching for a needle in a haystack sometimes. We decided to peel back the curtain by analyzing several critical performance metrics. Our team prioritized how approachable these companies are for individuals with less-than-perfect credit histories.
Speed was another heavyweight in our decision-making process. We wanted to know how quickly cash actually lands in your pocket. After that, we scrutinized the clarity of their fine print to ensure there are no hidden traps waiting in the weeds.
It is absolutely vital to understand how your credit score is impacted during the lookup process. You must distinguish between a soft inquiry and a hard inquiry before you sign anything. Skipping this step is like driving blindfolded into a thunderstorm.
A soft pull is quite gentle; it lets you browse interest rates and eligibility without leaving a mark on your rating. However, a hard pull involves a rigorous deep dive into your financial history. This formal investigation can trigger a short-term drop in your score.
We also took a hard look at how much you can borrow and how long you have to pay it back. A massive loan might look tempting, but high interest rates can quickly turn it into a financial anchor. It’s a slippery slope.
Imagine comparing two identical $5,000 loans. One carries a 15% APR, while the other hits you with 36% APR over 36 months. The math doesn’t lie, and the interest costs on that second option are astronomical. Our list favors companies with honest structures.
| Company | Borrowing Limits | Transfer Timing | Eligibility Rules | Standout Benefit |
|---|---|---|---|---|
| OneMain Financial | $1,500 – $30,000 | Within 1 hour | Check website | Local branch locations |
| Avant | Check website | Check website | Check website | Adaptable lending options |
| FastLoans CA | $1,000 – $35,000 | Within 24 hours | No hard credit pull | Authorized CA providers |
| Upgrade | Maximum $50,000 | Check website | Check website | Debit card cash back |
| VivaLoan | $100 – $15,000 | By the next day | All credit levels accepted | Small minimum loans |
| GreendayOnline | $100 – $5,000 | Same day | No credit check | Rapid emergency funds |
| United Finance | To $20,000 | Check website | Check website | Operating since 1922 |
Distinguishing Between Collateral-Backed and Non-Collateralized Debt
As you navigate your various borrowing opportunities, you will likely encounter two primary categories: secured and unsecured options. Grasping the nuance between these two paths is absolutely critical for maintaining your fiscal stability over time. Think of it as the dividing line between a minor inconvenience and a total catastrophe.
When you opt for an unsecured loan, such as the personal financing products offered by Upgrade or Avant, you aren’t required to provide any collateral. This means your home or your car title remains entirely out of reach for the bank. It’s a liberating feeling to borrow money without putting your physical belongings on the line.
Because the lender lacks a safety net to seize if you miss payments, they often charge higher interest rates to offset that added danger. Despite these steeper costs, many residents across California prefer this route because it protects their essential assets. It’s a trade-off many find worth making to keep their property safe.
On the flip side, a secured loan demands that you pledge something valuable, perhaps a savings account or your vehicle, to act as security. If you find yourself unable to meet the repayment terms, the lender possesses the legal authority to take that asset to recover their money. It’s a high-stakes gamble that carries significant weight.
While these types of loans frequently offer more favorable interest rates, the downside can be devastating. Losing a primary mode of transportation can throw your life into absolute chaos. Before signing anything, you must carefully balance the benefit of lower rates against the very real danger of losing your property.
Top-Rated Lending Options for Californians
1. OneMain Financial
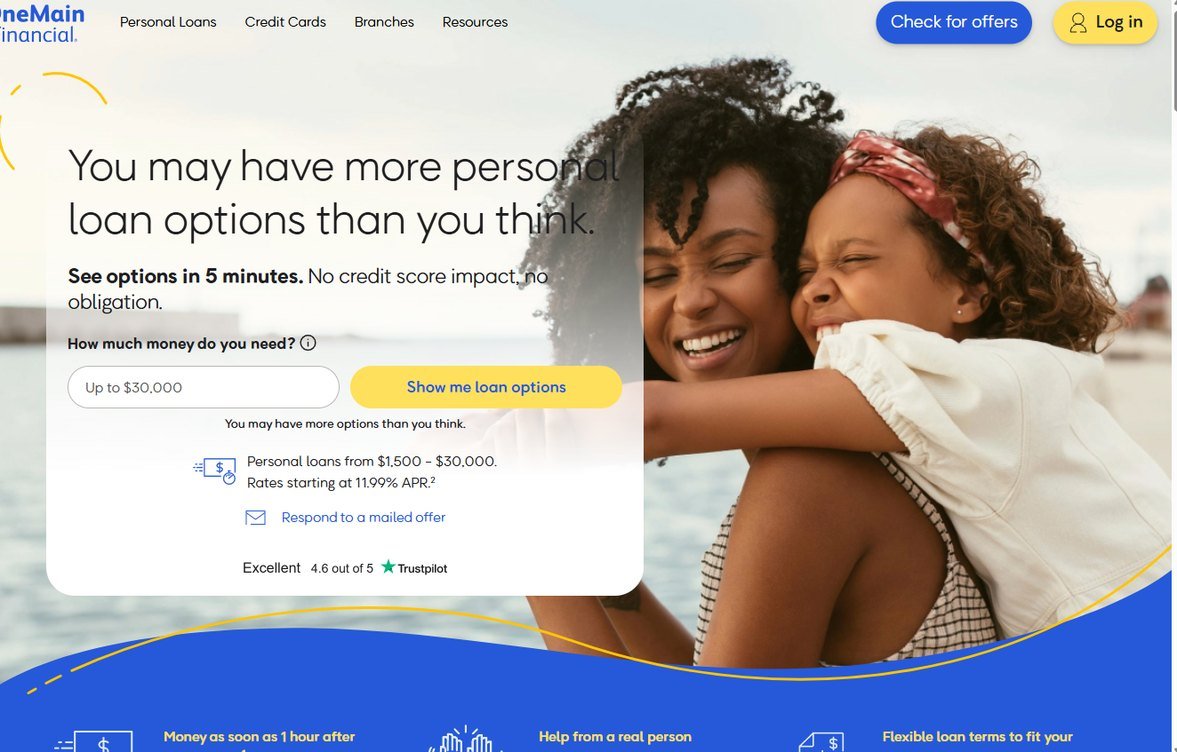
If you find yourself getting tangled up in fine print, OneMain Financial is a fantastic ally. They provide a human touch that’s hard to find in the digital age. With a massive network of over 1,300 branches, they bridge the gap between high-tech convenience and old-fashioned, face-to-face support.
For many, walking into a local office in Fresno or Sacramento makes the whole process feel much more grounded. It is much easier to grasp complex terms when you are sitting across from a real person rather than staring at a smartphone. This level of personal connection helps build real trust.
Their loan amounts are quite flexible, ranging from a modest $1,500 to a substantial $30,000. This versatility ensures you can tackle everything from quick fixes to major life expenses. Because they use fixed monthly payments, your budget stays steady even if the broader economy goes through a bumpy patch.
With terms lasting anywhere from 24 to 60 months, you can plan your finances with certainty. Rates begin at 11.99% APR, offering a structured pathway to handle your debt or cover sudden costs without the guesswork.
Pros:
- Large network of physical branches for hands-on assistance.
- Rapid funding, potentially hitting your account an hour after signing.
- Predictable budgeting through fixed monthly installments.
Cons:
- Requires more active engagement than purely online lenders.
2. Avant
Think of Avant as more of a financial partner than a simple cash provider. They focus on your long-term trajectory, offering tools designed to help you move forward. Whether you are eyeing a new credit card or a loan to consolidate debt, they act as a service rather than just a one-off transaction.
This approach is a godsend for anyone trying to roll several high-interest debts into a single, easier-to-manage monthly bill. They understand that no two financial paths are exactly alike. Consequently, they provide various solutions ranging from emergency cash to funds for home improvements.
Their digital setup is built for the person on the move. You can manage your finances while waiting for a bus or during a quick lunch break. It is an ideal choice for those needing specific tools to finally stabilize their economic situation.
Pros:
- Prioritizes your long-term financial progress.
- Provides a diverse menu of products like loans and credit cards.
- Seamless and modern digital interface.
Cons:
- Upfront clarity on specific rates and terms can sometimes be elusive.
3. FastLoans CA
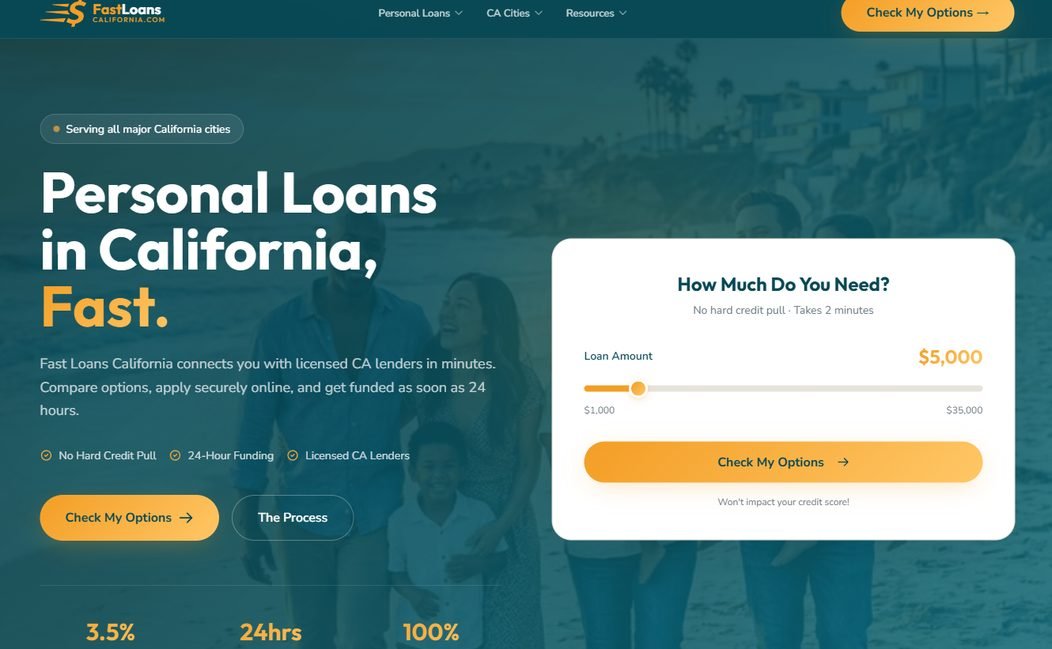
When a crisis strikes in California, FastLoans CA acts as a vital bridge to licensed state lenders. They prioritize speed above all else, often aiming to provide funding within 24 hours. This is perfect for families facing an immediate financial crunch.
Life moves fast, and so do emergencies like a burst pipe or a sudden medical bill. Their streamlined process takes only a few minutes to check your options. Best of all, you can explore your choices without a hard credit pull, keeping your score safe from unnecessary dips.
With limits reaching as high as $35,000, they can cover everything from minor repairs to significant household upgrades. Because they focus locally, they are deeply familiar with California’s specific lending laws, providing an extra layer of consumer protection.
Pros:
- No impact on your credit score when checking options.
- Extremely quick approval and funding cycles.
- Supports a massive number of California households.
Cons:
- Interest rates may be notably higher than traditional bank loans.
4. Upgrade
A heavyweight in the personal lending industry, Upgrade has helped over 8 million people navigate their finances. With loan ceilings reaching up to $50,000, they are a primary choice for major life milestones. They are particularly useful if you want to roll high-interest credit card debt into a single, manageable loan.
They offer much more than just basic loans; their suite includes rewards-based checking accounts. Some accounts even feature a 2% cash back perk on your purchases. This makes them a fascinating option for anyone wanting to merge their borrowing needs with their daily banking.
Integrating your main banking with your loan provider can make life much simpler. Instead of juggling a dozen different apps and statements, you can view your entire financial landscape in one dashboard. It’s a massive time-saver for the busy individual.
Pros:
- Generous loan ceilings reaching $50,000.
- Offers integrated checking accounts with built-in rewards.
- Quick rate checks that won’t hurt your credit score.
Cons:
- The best interest rates may require a stronger credit profile.
5. VivaLoan
Sometimes, you don’t need a mountain of cash; you just need a little help to get through the week. VivaLoan specializes in these smaller, manageable amounts. With loans starting at just $100, they are perfect for those specific, small emergencies like a sudden car repair.
The platform is built for pure speed, allowing you to complete a request in roughly 5 minutes. Once you get the green light, funds are usually deposited by the next business day. If you need money «yesterday,» this is the place to look.
The beauty of their system lies in its simplicity. They strip away the red tape and bureaucratic hurdles typical of big banks. This makes them highly accessible for people who just need a quick fix to a sudden problem.
Pros:
- Extremely low entry point with $100 minimums.
- Rapid turnaround, often by the next business day.
- An incredibly straightforward application process.
Cons:
- The maximum loan amount is capped at $15,000.
6. GreendayOnline
When you’re facing a true emergency, GreendayOnline provides specialized installment loans designed for those in a pinch. They cater specifically to individuals with poor credit by avoiding hard credit checks. For those shut out by traditional banks, this can be a genuine lifeline.
This is often the «last resort» for people dealing with bankruptcy or severely damaged credit scores. With amounts ranging from $100 to $5,000, it provides the liquidity needed for immediate crises. Their online application is designed for lightning-fast decisions.
While these are high-speed options, they are structured as installment loans. This means you pay them back over time rather than in one lump sum, which is much easier to manage than a standard payday loan. It is a straightforward way to get cash quickly.
Pros:
- Approvals occur without hard credit checks.
- Potential for extremely fast, same-day cash access.
- The online application is remarkably simple.
Cons:
- Payday-style structures can lead to very high interest costs.
7. United Finance
United Finance brings a sense of seasoned stability to the lending world, having been around since 1922. In an era of fly-by-night digital apps, their century-long history provides a comfort that many borrowers find essential. There is a certain peace of mind that comes with such longevity.
They offer a variety of products, including personal loans up to $20,000 and various auto loan options. Their goal is to keep the borrowing process simple and accessible. They are a great choice for those who want a traditional, reliable lending experience.
Having survived everything from the Great Depression to the modern digital revolution, their resilience speaks volumes. This history can give confidence to skeptical borrowers who are wary of unproven, internet-only platforms that might vanish overnight.
Pros:
- A massive history of established industry experience.
- Provides both auto and personal loan varieties.
- Offers a very personalized approach to accessibility.
Cons:
- Lacks the cutting-edge, instant digital features of some competitors.
How to Boost Your Approval Odds
Navigating the loan process with a low credit score can feel like walking a tightrope in a windstorm. However, you do not have to rely solely on luck to get a «yes» from a lender. While many people fixate on their FICO score, California lenders often cast a wider net, looking closely at your capacity to settle your debts on time.
Taking a moment to get your ducks in a row can prevent a cycle of rejections. Every time a lender pulls your report, it leaves a digital footprint that can impact your standing. By preparing thoroughly, you avoid those pesky hard inquiries that do nothing but complicate your financial profile.
Before you even sit down to fill out the digital forms, you should hunt down your essential paperwork. It is like preparing for a long road trip; you wouldn’t leave without a map and a spare tire. Generally, you will need to have the following items ready for review:
- A legitimate, government-provided ID, such as your passport or a driver’s license.
- Evidence that you live in California, like a lease document or a current utility bill.
- Verification of your earnings, including your most recent bank statements or your two latest pay stubs.
- Your Social Security number to confirm your identity.
If your income stream is a bit unconventional, such as if you are a freelancer or a gig worker, you need to be extra diligent. Lenders love consistency, so having neatly filed tax returns or a steady trail of bank deposits can be your secret weapon. It turns a «maybe» into a definitive «yes» when your earnings look organized and predictable.
Next, you ought to take a hard look at your debt-to-income ratio (DTI). Think of this as your financial breathing room; lenders want to ensure your monthly obligations don’t swallow up your entire paycheck. If your debt levels are currently eating away at your gross income, you might want to pivot slightly.
Sometimes, paying off a minor credit card balance before submitting your request can work wonders. This small tactical move improves your DTI and presents you as a much more stable candidate. It is often the difference between being seen as a risk and being seen as a reliable borrower.
Navigating Potential Financial Traps
Before you put pen to paper, you must grasp the full price of your debt. It is easy to get seduced by a small monthly installment. However, stretching out the repayment period can turn a minor debt into a mountain of interest. It is a classic case of «out of sight, out of mind» leading to financial ruin.
Imagine you secure a $5,000 loan. If the monthly bill is $200 and the term lasts 36 months, you will ultimately hand over $7,200. That extra $2,200 is the real price tag you are paying for that borrowed cash. Don’t let the low monthly number blind you to the true weight of the commitment.
Always demand the complete repayment figure in a single dollar amount. Relying solely on monthly figures is like looking at a map without seeing the destination. You need to know exactly how much leaves your wallet by the end of the contract.
Don’t let the lender rush you through the fine print. Many people trip over hidden administrative charges or unexpected service fees. These little costs can snowball into something much larger if you aren’t watching closely. It is better to be skeptical than to be surprised later.
Watch out specifically for «prepayment penalties.» These are essentially fines that punish you for being responsible and paying your debt off ahead of schedule. They are designed to keep you trapped in a cycle of interest payments.
You deserve the flexibility to settle your balance early without being penalized. If you find yourself with extra cash, you should be able to use it to slash your interest costs immediately. Being proactive is the best way to keep your credit healthy in the long run.
Slow down, weigh the different APRs, and make sure the loan structure dances well with your monthly budget. Ensure the math works with your actual lifestyle, not a theoretical version of your income. Taking a moment to be cautious now will save you from a massive headache down the road.

Top rated
-
 Cell phones
$250.00
-
sheath cell phone Samsung A20/ A30/ A50
$8.16
-
sheath cell phone Samsung A20s
$1.00
-
Samsung Bluetooth Headphones
$1.00
-
Xiaomi headphones
$10.00
Products
-
Cell phones
$250.00
-
Anker PowerCore portable charger
$39.99 – $55.99
-
Xiaomi headphones
$10.00
-
sheath cell phone Samsung A20/ A30/ A50
$8.16

