Get Fast Approval for Bad Credit Loans New York Today
Last updated: 2026-10-17
Navigating your finances in the Big Apple can often feel like being caught in a sudden Times Square blizzard. When your credit rating is struggling, finding a bank that won’t slam the door in your face feels like a Herculean task. Life in the five boroughs moves fast, and sudden medical emergencies or broken boilers can leave you scrambling for cash.
This resource was created specifically for New Yorkers facing sudden financial hurdles. We want to help you find trustworthy assistance without getting snagged by the predatory sharks lurking in local storefront shops. You really shouldn’t be forced to trade your rent money for a mountain of debt just to survive the week.
Balancing rapid access to funds with reasonable costs is the ultimate trick to staying upright in such a high-octane city. Picking a lender involves much more than just glancing at a single percentage. You must weigh how fast you get paid against what that cash will eventually cost you in the long run.
A cheap interest rate doesn’t mean much if the money arrives two weeks too late to stop an eviction. On the flip side, a loan that lands in your account instantly might carry massive APRs that make future payments a nightmare. It is a delicate dance between speed and sustainability.
We scrutinize how these companies run credit checks and how quickly they transfer funds into your personal account. We also dig into whether their fine print is crystal clear or riddled with sneaky pitfalls. Our assessment focuses on practical use for someone living in a fast-paced metropolis.
Our mission is to peel back the glossy marketing layers so you can find genuine financial help. We want to ensure you see the real value behind every offer. We’ve done the heavy lifting so you can make an informed decision for your future.
- SkyOne
- United Finance
- JetzLoan
- Experian
- GreendayOnline
Our Methodology for Reviewing NY Lending Services
Our team prioritized checking how easy it was for folks with bruised credit to get a foot in the door. We investigated if companies trigger a hard inquiry just to give you a preliminary quote. This is a big deal because those sudden dips in your score can sting quite a bit.
In a high-stakes environment like New York, where every point counts, knowing a lender uses a «soft pull» for estimates is a total game changer. It acts like a safety net for your financial reputation while you shop around.
When life throws a curveball, you don’t want to be left hanging. Whether it’s a busted transmission or a looming power shut-off, people need cash yesterday. We put a massive emphasis on how fast these companies actually move their money.
Speed shouldn’t come at the expense of being honest. We hunted for providers that get funds into your bank account promptly while being crystal clear about their rules. We wanted the real deal, not just empty promises of quick cash.
We also weighed the diversity of the loan amounts provided. A small $500 boost might fix a leaky fridge, but you might need $25,000 to sweep away the mountain of credit card debt that’s drowning your monthly budget. Variety is the spice of life, and it’s essential for financial needs.
Transparency regarding how you pay the money back was our North Star. We looked for genuine solutions rather than anything that looked like a debt trap. Our goal was to find lenders that act as a helping hand, not a heavy anchor.
We went on a hunt for «predatory lending» red flags. We kept a sharp eye out for massive origination fees that get tacked onto your initial principal. If the true cost of borrowing is buried under a mountain of fine print, they simply didn’t pass our test.
It is vital to understand the total cost of your credit over the entire life of the loan. We refused to include any company that tries to hide the real price tag from their customers. Honesty is our non-negotiable standard for this list.
| Company | Funding Range | Payout Speed | Credit Standards |
|---|---|---|---|
| SkyOne | $500 – $50,000 | see site | Personal Loans available |
| United Finance | see site | see site | Installment loans available |
| JetzLoan | $500 – $35,000 | As little as 24 hours | No hard credit pull |
| Experian | $2,000 – $50,000 | Same-day funding available | see site |
| GreendayOnline | $100 – $5,000 | As soon as the same day | Bad credit welcome |
Top-Rated Lending Options
1. SkyOne
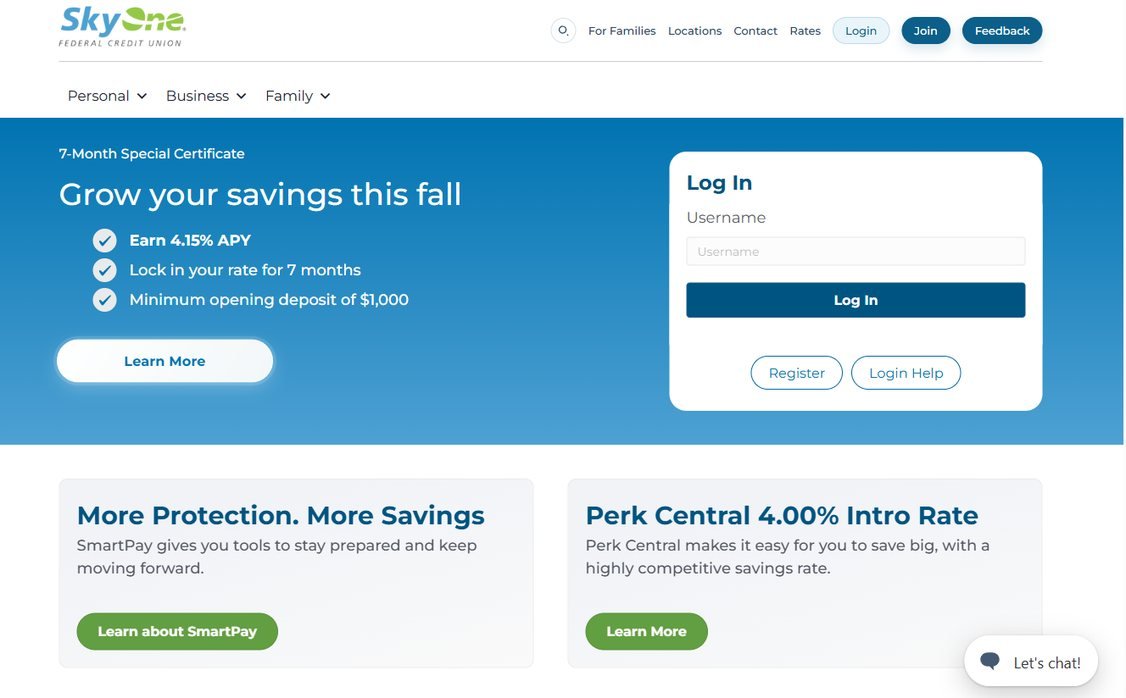
As a federal credit union, SkyOne takes a much more human approach to your finances. Unlike the giant commercial banks that rely on cold, automated algorithms to say «no,» this institution is owned by its members. This structural difference often allows for a more comprehensive review of your unique situation.
Whether you need a personal loan or a line of credit to steady your ship, they offer real assistance. Their interest rates for personal loans can dip as low as 13.99% APR, making them a much cheaper alternative to the high-interest credit cards sitting in your wallet. It is a smart way to dodge the debt trap.
If you are staring down a massive project—like fixing up your kitchen or saving for a car down payment—their high limits of up to $50,000 offer plenty of breathing room. It is an excellent choice for those who want to prioritize long-term stability over a quick, temporary fix.
Pros:
- Personal loan APRs can start at 13.99% for competitive rates.
- Borrowing limits reach as high as $50,000.
- Provides both flexible lines of credit and standard loans.
Cons:
- You may need to meet specific credit union membership criteria.
2. United Finance
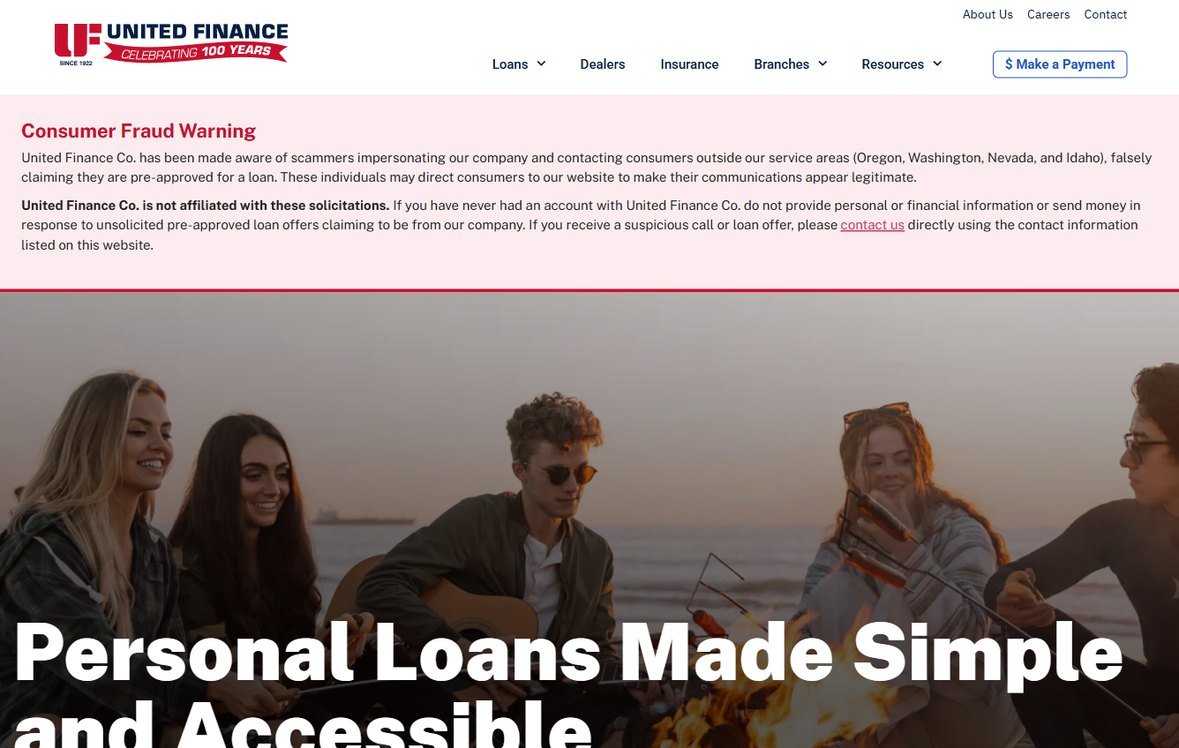
Since 1922, United Finance has been navigating the financial waters, bringing over a century of expertise to every client. They lean heavily into installment loans, which act as a steady anchor for your budget. Unlike payday loans that feel like a sinking ship, these loans use fixed repayments of principal and interest.
This structure offers a predictable rhythm for your monthly spending. It is a far cry from revolving debt, where compounding interest can make it feel like you are running in place while the principal stays untouched. They take security seriously too, constantly warning folks about scammers trying to ride their coat-tails.
For residents in New York, staying vigilant against predatory texts and emails is vital. Having a lender that has survived a hundred years of economic storms provides a sense of institutional strength that new fintech startups simply cannot match. It is stability you can count on.
Pros:
- A massive legacy and proven track record dating back to 1922.
- Utilizes predictable installment loans instead of dangerous payday cycles.
- Maintains a robust focus on protecting consumers from fraud.
Cons:
- Availability is restricted to certain states, including Nevada and Oregon.
3. JetzLoan
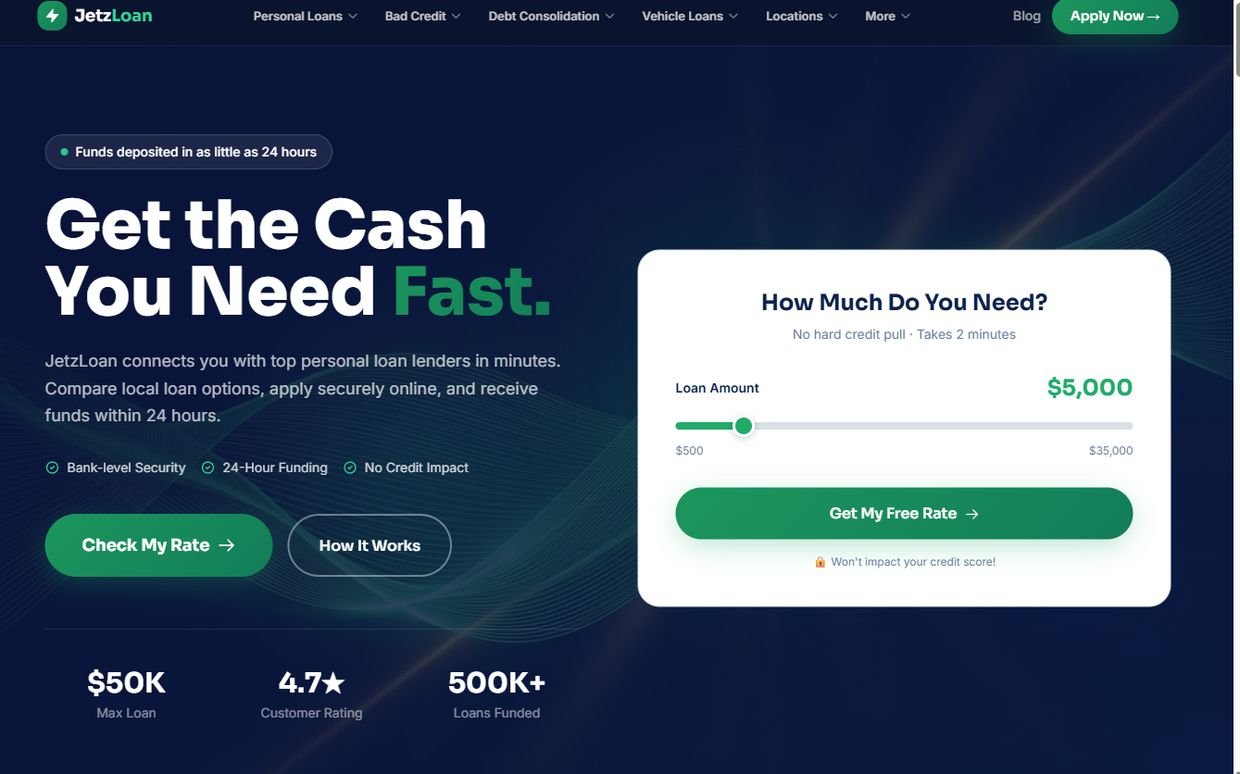
When you are caught in a financial bind and need cash yesterday, JetzLoan is built for lightning speed. They specialize in matching users with premier lenders in a matter of minutes. The real kicker? You can scout your rates without a hard credit pull, keeping your score perfectly intact.
This pre-qualification stage is a total game-changer for your credit health. Many people fear that every application is a direct hit to their credit score, but that isn’t the case here. You can shop around for the best deal without any immediate penalty to your report.
Forget the endless piles of paperwork found at old-school banks. This interface is built for the person on the move, perhaps filling out a form on a smartphone while riding the subway. With funds potentially arriving in your account in as little as 24 hours, it is a lifesaver in a pinch.
Pros:
- Perform rate checks without the sting of a hard credit pull.
- Rapid funding that often hits your account within a day.
- A streamlined application that takes roughly two minutes.
Cons:
- There is a $35,000 cap on the maximum loan amount.
4. Experian
Experian is a titan in the credit monitoring world, and their loan offerings are no exception. They live and breathe the science of credit scoring. They offer personal loans between $2,000 and $50,000, with repayment windows stretching from 24 to 72 months to suit your lifestyle.
Choosing a longer term can lighten the load on your monthly cash flow, though it does mean paying more in interest over time. They are particularly effective if you want to use their ecosystem to actually improve your standing. Tools that report on your rent or utility payments can give your score a much-needed lift.
This creates a beautiful, upward cycle for your finances. You can use a loan to clear a hurdle, then use Experian’s tools to ensure your score is much higher when it’s time to buy a house or a car. It turns a momentary setback into a long-term win.
Pros:
- Certain loan types are eligible for same-day funding.
- Repayment schedules can be stretched up to 72 months.
- Offers integrated resources to help elevate your credit score.
Cons:
- They cannot guarantee specific score increases or loan approvals.
5. GreendayOnline
GreendayOnline serves those who need a small, quick cash injection to plug a temporary gap. Their installment loans range from a modest $100 up to $5,000. This is a niche tool designed for emergencies where the main goals are ease of use and sheer speed.
Think of this as a micro-loan for those unexpected life hiccups. While it won’t help you tackle a massive mountain of debt, it is a fantastic bridge to get you from one paycheck to the next. The entire process happens online, which is perfect for a busy New Yorker on the go.
They are particularly welcoming to those with less-than-perfect credit, providing a path to cash without a mountain of paperwork. It is a straightforward, no-nonsense fallback for anyone who has been tripped up by past credit issues but needs to keep moving forward.
Pros:
- Very low entry point with minimums starting at $100.
- Rapid approval processes with same-day cash options.
- Tailored specifically to assist those with bad credit.
Cons:
- The maximum loan amounts are quite small compared to other lenders.
Navigating Your Loan Choices: A Practical Framework
Once several lenders start throwing proposals your way, it is incredibly easy to get lost in a sea of conflicting decimals and deadlines. The sheer volume of data can make your head spin like a top.
To keep your feet on the ground, you need a method to sort the wheat from the chaff. Navigating this landscape requires a clear-eyed strategy to ensure you aren’t walking into a financial trap.
Don’t just glance at the surface level; dive deep into the fine print. Use this checklist to weigh your options and find the deal that actually fits your life.
- Focus on the APR over basic interest: It is a common mistake to focus solely on the interest rate. While that tells you the price of the principal, the Annual Percentage Rate (APR) is the real truth-teller because it incorporates origination and processing fees.
- Establish your personal monthly ceiling: Before signing anything, sit down with your actual bank statements. If your budget only permits an additional $150 in monthly expenses, reject any plan requiring a $200 commitment, regardless of how low the interest might seem.
- Hunt down any prepayment penalties: Some creditors will slap a fee on your account if you try to settle your debt ahead of schedule. If a sudden windfall or a tax refund is in your future, ensure you can pay the loan early for free.
- Clarify the actual arrival time: If you are facing a sudden crisis, you need cash yesterday. Ask your lender, «When exactly will these funds be cleared and available in my bank account?» Remember, an approval is merely a promise, not liquid cash.
Navigating the Hazards of the New York Credit Landscape
The sheer volume of financial options in the city can leave even the most seasoned borrower feeling like they are lost in a concrete jungle. Unscrupulous lenders often try to corner you into making split-second decisions through high-pressure salesmanship.
If a company starts hounding your phone with endless calls, take it as a red flag. Watch out for phrases like «act now or face immediate rejection» or claims that this is your «last chance» to secure funds. Real, reputable lenders behave differently; they act with professionalism and will never force you to skip over the fine print.
It is also vital to watch out for a dangerous cycle known as «loan stacking.» This happens when a person grabs a tiny, high-interest loan specifically to settle a previous high-interest debt. It feels like you are putting out a fire, but you are really just pouring gasoline on the flames.
By shifting debt around, you aren’t actually making progress because interest rates continue to stack up against you like falling dominoes. If your strategy involves borrowing a second loan just to cover the first, you have likely hit a wall. At that point, it is time to pull the emergency brake and consult a debt counselor.
Lastly, do not let a slick website fool you into thinking a lender is trustworthy. In our digital age, a clean design is nothing more than the bare minimum requirement for a professional appearance. A glossy interface does not guarantee that the business is actually stable or honest.
Always do your homework to verify that any online lender is properly registered to do business within New York. Look for a verifiable physical office address and check their history of real customer feedback. True credibility is built on transparent terms and a solid, long-term reputation, not just a pretty layout.
Making Smart Choices with Your Credit Options
Pause for a second and catch your breath before you put pen to paper. When an approval comes through lightning-fast, it is incredibly easy to lose sight of the big picture. You need to scrutinize the actual price tag of every cent you borrow.
Always dig deeper into the fine print to hunt for hidden costs like origination fees or penalties for paying the debt off early. These little surprises can turn a manageable loan into a massive financial burden. For instance, if you borrow $1,000 but a $100 setup fee is tucked away in the terms, the interest rate is not actually what it seems on the surface.
Don’t let the siren song of multiple quick fixes lure you into a trap. Taking out several tiny loans from various lenders just to patch up one big hole in your budget is like trying to fix a leaky boat with more holes.
This habit often triggers a debt snowball that becomes nearly impossible to stop once it starts rolling. Instead of chasing multiple deadlines, try to bundle your financial needs into a single, steady monthly installment. It keeps your monthly outlook clear and saves your sanity in the long run.
Trying to track five different interest rates and a dozen due dates is a recipe for a headache. Your brain thrives on consistency, and managing one predictable payment is far simpler than juggling a chaotic mess of various creditors every month.

Top rated
-
 Cell phones
$250.00
-
sheath cell phone Samsung A20/ A30/ A50
$8.16
-
sheath cell phone Samsung A20s
$1.00
-
Samsung Bluetooth Headphones
$1.00
-
Xiaomi headphones
$10.00
Products
-
Cell phones
$250.00
-
Anker PowerCore portable charger
$39.99 – $55.99
-
Xiaomi headphones
$10.00
-
sheath cell phone Samsung A20/ A30/ A50
$8.16

