Best Rates for a 520 Credit Score Personal Loan Online Now
Last updated: 2026-10-16
Navigating life with a 520 credit score can feel like trekking through thick sludge during a thunderstorm. It is a grueling uphill battle. Often, the banking industry shuts its doors tight the moment your digits slide into the 500s.
You might find yourself stuck in a relentless loop. One moment you are hunting for a lifeline, and the next, your mailbox is overflowing with formal denials. It is enough to make anyone want to throw in the towel.
Such a low rating usually stems from several heavy burdens. Perhaps you have struggled with overdue bills, maxed out your revolving credit, or are still recovering from a bankruptcy or a collection notice. These setbacks leave a mark.
Beyond the bank balance, the mental fatigue is real. Constantly hearing «no» from every major bank can weigh on your spirit just as much as the actual debt. It feels like the world is constantly moving on without you.
We decided to hunt down lenders that care about the person, not just the digits. This list highlights companies willing to peer past that one stagnant number. Sometimes, you just need a hand to get back on your feet.
When life throws an unexpected curveball, like a sudden car repair or a hospital invoice, you cannot wait around. You need a fast answer and a straightforward process. Waiting weeks for a human to review a file is simply not an option.
Our team cut through the clutter to find genuine options for those in a pinch. We specifically sought out firms that weigh different factors. They look at your steady paycheck or your banking history to gauge your reliability.
- Max Cash
- Avant
- JetzLoan
- Acorn Finance
- NetCredit
- Upgrade
Our Methodology for Vetting Lenders
Navigating the financial landscape with a 520 credit score feels like trekking through deep mud. It is a steep uphill battle for anyone trying to secure much-needed capital. Our main goal was finding companies that extend a helping hand to those with blemished histories rather than shutting the door immediately.
We zeroed in on streamlined web-based providers that can finish a request in a mere ten minutes or less. It is not just about the numbers on your report, though. We also scrutinized the breadth of their offerings to ensure they could meet diverse needs.
Sometimes you just need a tiny lifeline for a sudden electric bill. Other times, you are looking to renovate your kitchen. Consequently, we only recommended institutions that maintain a wide menu of loan amounts to suit any situation.
Protecting your rating is also a top priority in our research. We hunted for the «soft pull» option, which lets you browse rates without any risk to your standing. This prevents the dangerous habit of «shotgunning» multiple requests at once.
Applying wildly for many different loans in a desperate scramble can wreak havoc on your profile. We want to ensure you don’t accidentally dig a deeper hole while searching for a lifeline. It’s about being smart with your inquiries.
Lastly, we took a hard look at how these companies communicate their costs. For someone sitting at 520, a surprise prepayment penalty can feel like a punch to the gut. We focused on transparency to keep you out of the debt trap.
Lenders must be crystal clear about their total APRs before you ever sign a contract. We believe you deserve to know the full cost of borrowing before you dive into the deep end. No hidden surprises allowed here.
| Provider | Borrowing Limits | Transfer Speed | Effect of Checking Rates |
|---|---|---|---|
| Max Cash | $250 – $10,000+ | Minutes | No Obligation |
| Avant | See site | See site | See site |
| JetzLoan | $500 – $35,000 | As little as 24 hours | No impact |
| Acorn Finance | See site | See site | No impact |
| NetCredit | Up to $10,000 | Same-day available | No impact |
| Upgrade | Up to $50,000 | Fast funding | Won’t impact score |
Top-Rated Lenders for Challenging Credit Situations
1. Max Cash
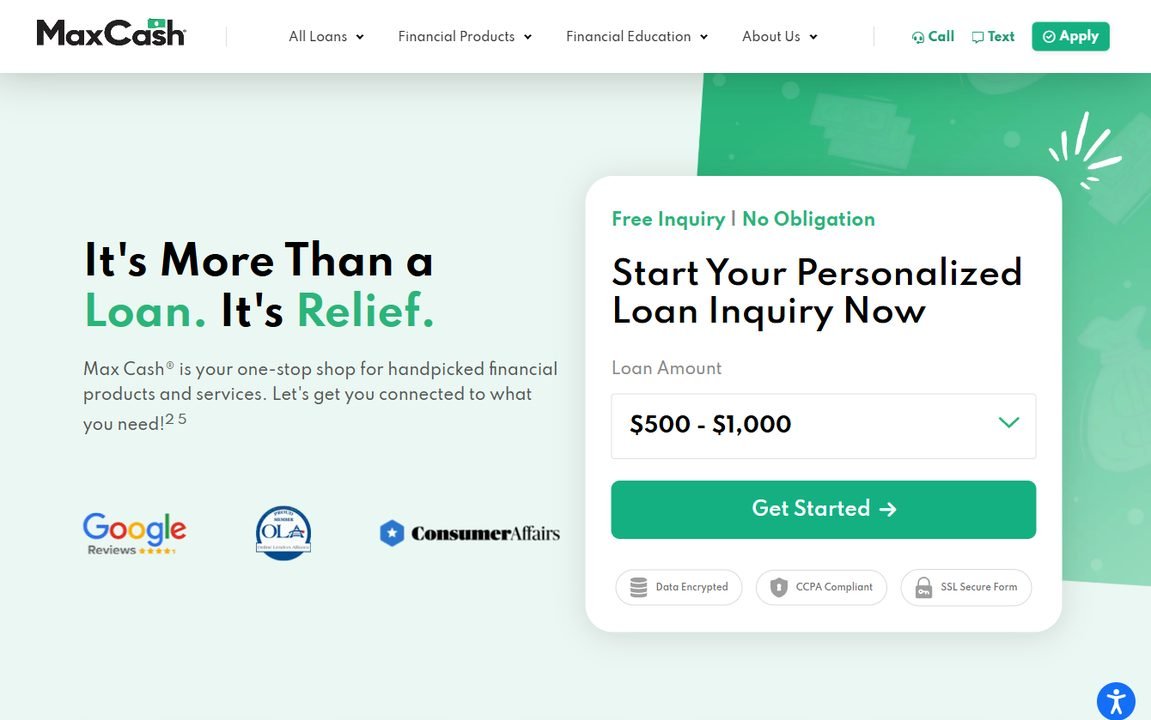
When conventional banking institutions slam the door on your application, Max Cash steps in to act as a vital lifeline. They provide a diverse array of financial products, ranging from modest personal outlays to much larger installment-based debt options. If you find yourself in a tight spot, they aim to deliver solutions within minutes rather than waiting several days.
This makes them a perfect choice for «bridge financing,» a strategy used to span the gap between two incoming funds, like a paycheck or a tax refund. It is a premier option for individuals requiring immediate cash flow to navigate unexpected emergencies. They act as a safety net when timing is everything.
Their loan availability is highly versatile, starting at just $250 and stretching well past the $10,000 mark. This flexibility is a godsend for anyone whose current economic circumstances demand rapid and adaptable movement. Because the entry threshold is so low, they are an ideal instrument for small, micro-level needs that do not require long-term debt.
Pros:
- Extensive range of loan amounts from $250 to over $10,000.
- Rapid processing that takes only minutes.
- No commitment is required for your initial personalized quote.
Cons:
- The emphasis on high-speed liquidity may result in increased interest rates.
2. Avant
Avant operates on the principle that a solitary digits-only score fails to capture your entire financial character. Their mission is to propel you toward better fiscal health by providing instruments to manage existing debt or cover sudden household costs. They serve as a structured path for those eager to build a more solid economic foundation.
Unlike many lenders that rely solely on FICO metrics, Avant’s underwriting process may take your bank history or steady job tenure into account. Whether your goal is a new credit card or a specific loan for fixing up your home, they present various tailored solutions for your journey.
They are especially beneficial for those who have moved past the rock bottom of the credit spectrum and want a steady ally for long-term goals. As your score climbs from a 520 toward the 600 mark, Avant can function as a long-term partner in your recovery rather than a mere quick fix.
Pros:
- Provides a variety of products, including credit cards and consolidation options.
- Structured to facilitate upward financial mobility.
- Versatile solutions tailored to different life stages.
Cons:
- Certain minimum score requirements might disqualify those with the very lowest ratings.
3. JetzLoan
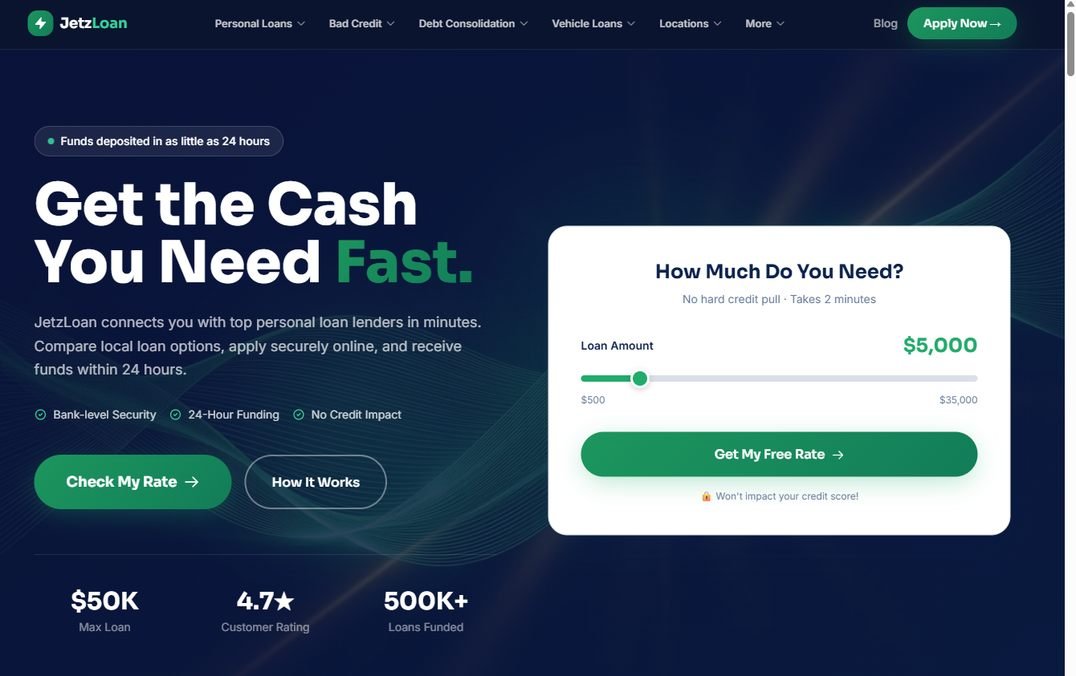
If the agony of waiting for a check to clear is too much, JetzLoan serves as a breath of fresh air. They bridge the gap between you and top-tier lenders in mere minutes, ensuring the comparison stage is incredibly snappy. It is an incredibly efficient, streamlined method for the modern, time-pressed borrower.
Instead of losing hours to endless, repetitive paperwork, JetzLoan’s marketplace architecture handles the heavy lifting on your behalf. They maintain a high reputation among users and have facilitated the funding of over 500,000 loans. With the possibility of receiving your funds in as little as a 24-hour window, speed is their middle name.
The capacity to investigate rates without a hard inquiry on your credit report is a massive safeguard for your score. This is vital; if you are hovering at 520, even one or two unnecessary hard pulls can send you tumbling into the 400s, making you look much less desirable to future lenders.
Pros:
- High potential for receiving funds within a 24-hour period.
- Checking rates is done without a hard credit pull.
- Boasts a high rating for customer satisfaction.
Cons:
- The speed at which you get funded is largely dependent on your specific lender match.
4. Acorn Finance
Acorn Finance operates as a specialized player, specifically catering to those looking to finance home improvement endeavors. They function as a marketplace, linking you with an assortment of different lenders. This is a game-changer if you are looking to remodel a kitchen or build a new deck to boost property value.
For many homeowners, the house is their greatest wealth-building tool, and using a loan to enhance that asset is a smart way to grow net worth even with low credit. They feature a unique model where contractors can provide financing with absolutely no dealer fees involved.
This makes them a standout choice for large-scale, project-oriented financial needs. You can view custom rates without a single dent in your credit score, which is essential when your standing is already shaky. For instance, if a new roof is required, you can use Acorn to scan multiple home-improvement lenders to find the best APR for your specific profile.
Pros:
- Focuses specifically on contractor financing for home projects.
- Checking rates results in no impact on your credit score.
- Certain contractor options come with zero dealer fees.
Cons:
- The niche focus may make them less suitable for general, everyday cash needs.
5. NetCredit
NetCredit markets itself under the banner of «Credit to the People,» a phrase that emphasizes you are far more than just a data point. This philosophy is baked into their use of sophisticated algorithms that look at your total financial picture, going well beyond a simple FICO score.
By analyzing your banking activity, they can assess your true ability to repay, which is a massive advantage for those with thin credit histories or recent score drops. They provide various personal loans and lines of credit, with the potential to secure funding on the very same day.
This is a lifesaver for anyone facing a sudden, pressing obligation, like a car repair that stands between you and your job. They strive to provide an empathetic and transparent lending experience for those often overlooked by the big banks, making the whole process feel much more human.
Pros:
- Same-day funding options are readily available.
- Employs advanced algorithms to look past the credit score alone.
- Verifying your eligibility does not harm your FICO score.
Cons:
- Borrowing limits are capped at a relatively modest $10,000.
6. Upgrade
Upgrade is a titan in the personal lending sector, serving an enormous community of borrowers. They offer substantial capital, reaching up to $50,000, making them an excellent choice for major life milestones or rolling over high-interest debt. If you are struggling under the weight of multiple credit card balances, this could be your way out.
Using an Upgrade loan to consolidate that mounting debt into one single, lower-interest installment loan can be a powerful catalyst for credit repair. Their digital platform is built for extreme convenience, allowing you to view your potential rates in a matter of minutes.
They also integrate unique features like cash back on various purchases, which can help you reclaim some financial ground while you work on your credit standing. This dual-action approach—offering a loan while also providing cash-flow management tools—makes them a very comprehensive financial companion.
Pros:
- Generous loan ceilings reaching up to $50,000.
- Rapid rate checking and fast funding processes.
- Extra perks like cash-back checking accounts.
Cons:
- The wide array of financial products might feel overwhelming if you only want a simple loan.
Navigating the Price of Subprime Lending
If your credit score is hovering around 520, you should prepare yourself for a bumpy ride. Borrowing capital becomes significantly more taxing compared to a borrower boasting a 750 rating. Think of interest rates as a «risk premium,» a buffer that banks demand to offset the chance that you might default on your obligations.
You really need to get a grip on the distinction between simple and compound interest structures. Simple interest only targets the original principal. However, compound interest applies to the principal and any unpaid interest that has already accrued. This can cause your debt to snowball into a mountain of trouble if you only stick to minimum payments.
Before signing anything, hunt down the «Total Cost of Loan» figure. A lender might dangle a $150 monthly payment to lure you in, which feels quite digestible at first glance. But if that debt is stretched across 60 months, you could end up paying back $9,000 for a $5,000 loan.
That represents a $4,000 fee just for the privilege of accessing that cash. Always ask your lender: «How much total interest will I pay over the life of this loan?» Asking this one question can save you thousands of dollars and prevent years of grueling financial struggle.
Pathways to Boost Your Credit Rating Following a Loan Approval
Viewing a loan secured with a 520 score as a mere quick fix for an overdue bill is a mistake. Instead, treat this capital as a strategic tool designed to fortify your financial foundation. If you are consolidating various debts, consider this extra space a fresh start to clear those balances entirely.
However, there is a massive trap waiting for the unwary. If you wipe the slate clean on a credit card using loan funds, but then proceed to swipe that card again immediately, you’ve essentially doubled your financial burden. This cycle will cause your score to crash even harder than before.
Think of your credit score like a garden; it requires consistent tending to flourish. If you use this loan to plant seeds of stability, you must protect them from the storms of impulsive spending. A single slip-up can undo all the hard work you have put into your recovery.
To reap the maximum benefits of your new loan and watch those numbers climb, stick to these vital habits:
- Set up automatic transfers: Missing a single installment can cause your score to plummet by 50-100 points. At the very least, ensure your minimum monthly payments are automated so you never miss a deadline.
- Keep your usage low: If your loan was meant to settle credit card debts, make sure those cards stay below 30% utilization. This tactic is often the fastest way to see a meaningful jump in your rating.
- Hold off on new credit for 6-12 months: Once your finances begin to steady, resist the temptation to open fresh lines of credit. Your score requires time to demonstrate that your new, consistent repayment habit is here to stay.
Steering Through Your Borrowing Journey
Navigating the path to a new loan with a 520 credit score feels like walking a tightrope during a storm. Every decision you make carries significant weight. A common pitfall involves firing off several applications simultaneously. Every time a lender performs a «hard pull» on your profile, your score takes a hit, potentially deepening your financial hole.
Instead of rushing blindly, you should hunt for lenders offering «soft pull» inquiries. This method lets you test the waters without any damage to your standing. It is essentially window shopping for interest rates. You can scout the market to find the most favorable terms without the sting of repeated credit inquiries.
Don’t let the allure of quick cash blind you to the long-term consequences. While an immediate injection of funds might soothe a current crisis, high interest rates can snowball into an unmanageable debt mountain. It is crucial to scrutinize the fine print before signing any paperwork.
When comparing options, do not simply look at the monthly installment amount. Instead, focus on the total cost of the borrowing over the entire life of the loan. You need a financial tool that acts as a ladder toward stability, rather than a weight that keeps you anchored in place.
Keep a sharp eye out for «prepayment penalties» hidden within the contract. If you happen to receive a bonus or an unexpected gift, you might want to settle your debt ahead of schedule. However, some predatory lenders will slap you with extra fees for being proactive with your payments.
Ideally, you want a partner that celebrates your financial progress. Look for lenders that reward your efficiency rather than those that punish you for paying them back early. Finding a flexible agreement is the key to reclaiming your financial freedom.

Top rated
-
 Cell phones
$250.00
-
sheath cell phone Samsung A20/ A30/ A50
$8.16
-
sheath cell phone Samsung A20s
$1.00
-
Samsung Bluetooth Headphones
$1.00
-
Xiaomi headphones
$10.00
Products
-
Cell phones
$250.00
-
Anker PowerCore portable charger
$39.99 – $55.99
-
Xiaomi headphones
$10.00
-
sheath cell phone Samsung A20/ A30/ A50
$8.16

