Best 500 Credit Score Personal Loan Options to Apply for Now
Last updated: 2026-10-16
Navigating a financial downturn with a 500 credit score can feel like wandering through a heavy mist without any direction. It is a common misconception that a low score acts as a permanent barrier to credit. In reality, it is more like a steep hill that you simply have to climb.
Success hinges on your ability to pinpoint lenders who look at the person behind the data. Instead of getting discouraged by a single digit, you should focus your energy on finding companies that offer a lifeline. Finding the right partner can change your entire trajectory.
A score of 500 generally lands in the «very poor» bracket. If you apply for a mortgage with a major bank or try for a premium credit card, expect a swift «no» from their automated systems. The traditional doors might be bolted shut for now, but the market is far from empty.
You don’t need to give up on borrowing altogether. You just need to pivot your approach. Instead of chasing standard banks, you should seek out specialty lenders who are comfortable working with non-traditional profiles. It is all about changing your target.
When you are hunting for capital, don’t just grab the first check you see. You must ensure the contract won’t become a weight around your neck later. High interest rates act like a slow leak in a boat, eventually dragging you under if you aren’t careful.
Let’s look at the numbers to see how much this matters. If you borrow $5,000 at a 25% APR, your monthly burden is manageable. However, if that same $5,000 loan carries a 36% APR over 36 months, the math changes drastically.
That extra percentage point can lead to thousands in additional interest payments. That is money that could have bolstered your emergency fund or helped pay down other debts. This list highlights lenders that balance quick access with a focus on those rebuilding their lives.
- Avant
- OneMain Financial
- FastLendGo
- Reprise
- United Finance
- OppLoans
Our Method for Assessing Lenders
Our primary mission involved scouting for financial institutions that don’t turn their noses up at borrowers with «poor» credit standings. Because a 500 score can act like a locked door at traditional banking institutions, we centered our search on specialists who thrive in the subprime market.
We placed a heavy premium on companies that provide straightforward application journeys. It is crucial that a seeker can explore their options without seeing an immediate dip in their FICO score due to the initial inquiry process.
A «soft pull» is a lifesaver in these circumstances, letting you glimpse your potential interest rates and loan terms without the damage of a «hard pull.» When your credit is already teetering on the edge, you need to window shop without making a mess of your report.
The ability to get cash into your hands quickly was another cornerstone of our vetting process. If you are staring down a mountain of medical bills, a broken-down vehicle, or an overdue electricity notice, you don’t have the luxury of waiting weeks for a decision.
Consequently, we gave the spotlight to lenders capable of rapid approvals or even same-day payouts, as long as their repayment structures weren’t predatory. We focused heavily on the «time-to-cash» metric to see how fast a user moves from clicking «submit» to seeing funds in their bank account.
Calculating the Real Price of Borrowing with Subpar Credit
Before you sign on the dotted line with any company featured here, you must confront the cold, hard math behind expensive debt. When your score hovers around the 500 mark, you are essentially walking into a storm of high-interest debt. Lenders see that number and immediately label you as a risky bet for their money.
To protect their own pockets, these institutions tack on much steeper Annual Percentage Rates (APRs) to offset potential losses. It is crucial to realize that the interest rate and the APR are not the same thing. Think of the APR as the «true» cost, as it bundles the base rate with sneaky origination charges and miscellaneous lender fees.
Imagine you are trying to navigate a dark forest without a compass; that is what it feels like trying to compare these numbers without knowing the APR. You need a crystal-clear view of your long-term obligations before you commit to a single payment. Relying solely on the interest rate is a recipe for a financial headache that lasts for years.
Look closely at these hypothetical scenarios for an individual carrying a 500 credit score to see how quickly things spiral:
| $3,000 Principal | Annual Percentage Rate | Duration | Monthly Installment | Extra Cost Over Time |
|---|---|---|---|---|
| $3,000 | 15% (Good Credit) | 24 Months | $145.46 | $491.04 |
| $3,000 | 30% (Fair Credit) | 24 Months | $171.18 | $1,108.32 |
| $3,000 | 45% (Poor Credit) | 24 Months | $199.63 | $1,791.12 |
The data above reveals a brutal reality: a simple doubling of your interest percentage can skyrocket your total repayment amount by more than three times. It is a massive difference that can make or break your budget. You might find yourself working just to stay in the same place financially.
Because of this, your primary objective should be finding a partner, not just a predator. You need a lender that offers a ladder to help you climb out of the credit trenches. Choosing a provider that actively assists in score improvement, rather than one designed to bleed you dry with interest, is your most vital move.
Top-Rated Borrowing Options Compared
Finding the right lender feels like searching for a needle in a haystack when your credit history is less than stellar. You might feel like you’re walking a tightrope without a safety net.
Different institutions offer varying degrees of flexibility. Some focus on rapid cash infusions, while others prioritize extended repayment windows to ease your monthly budget pressures. It is vital to weigh these features carefully.
I once spoke with a man named Elias who was desperate for quick repairs. He thought he was out of luck due to his score. However, choosing the right provider changed everything.
Below, we have laid out a quick snapshot of several prominent players in the lending market. This helps you see at a glance who might be the best fit for your specific needs.
| Provider | Available Funds | Duration | Payout Velocity | Eligibility Note |
|---|---|---|---|---|
| Avant | Visit website | Visit website | Visit website | Accommodates lower scores |
| OneMain Financial | $1,500 – $30,000 | 24 – 60 months | Within 60 minutes | Visit website |
| FastLendGo | Visit website | Visit website | Visit website | No credit or poor history |
| Reprise | Visit website | Visit website | Visit website | Visit website |
| United Finance | Maximum $20,000 | Visit website | Visit website | Visit website |
| OppLoans | Visit website | Visit website | Within the same day | FICO score is untouched |
Keep in mind that «fast» is a relative term in the banking world. While some promise money by lunchtime, others might take a few business days to clear the hurdles.
Don’t let a low score keep you from exploring your avenues. Many companies have built their entire business model around assisting people who find themselves in tricky financial spots.
Always read the fine print before signing on the dotted line. A quick glance at the interest rates can save you from a massive headache down the road when you’re trying to balance your checkbook.
Top-Rated Lending Institutions
1. Avant
Think of Avant as a financial companion walking beside you on your journey toward stability. They don’t just hand over cash; they craft specialized instruments like installment loans and credit cards tailored to your current life chapter. Their mission revolves around equipping people with the necessary gear to navigate debt or weather unexpected storms.
While many predatory sharks thrive on short-term «payday» traps, Avant plays a much longer game. They aim to cultivate lasting bonds with their clients rather than just completing a transaction. It’s a refreshing change of pace for those seeking more than a quick fix to their cash flow issues.
For anyone currently drowning in a sea of high-interest credit card debt, an installment loan from Avant might be your life raft. By rolling those various balances into a single monthly payment, you can finally breathe easier, assuming the interest rates align with your goals.
Pros:- Provides a variety of financial instruments, including debt consolidation and credit cards.
- Aims to empower borrowers toward achieving significant financial milestones.
- Offers versatile solutions that adapt to different stages of life.
- Specific interest rates and the exact terms for every credit tier aren’t always publicly listed.
2. OneMain Financial
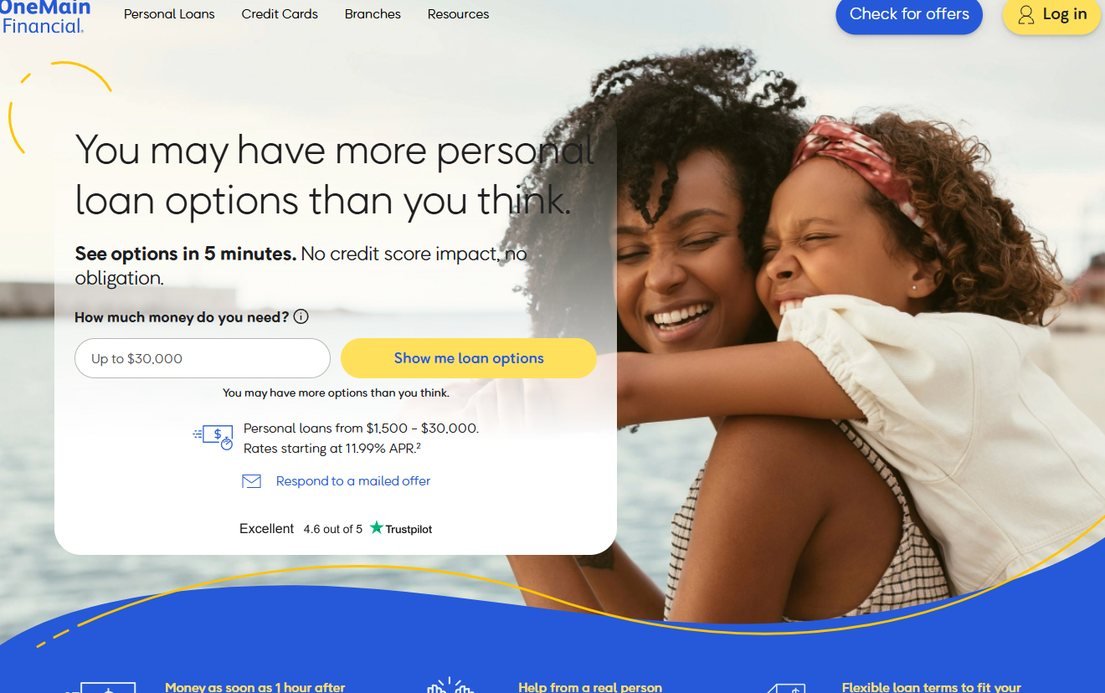
Sometimes, you just need to look someone in the eye to explain your situation. That is where OneMain Financial shines, offering a human element that most digital-only lenders simply cannot match. With a massive footprint of over 1,300 physical branches, they are always just around the corner.
This physical presence is a golden ticket for entrepreneurs or anyone with non-traditional income streams. When a computer algorithm hits a wall, a real person can look at your story and find a way forward. This personal touch can often unlock much better terms than a cold, automated process.
Whether you need $1,500 for an emergency or $30,000 for a major project like a new roof, they have you covered. If you are in a rush, you might see the funds in your account just sixty minutes after signing the paperwork.
Pros:- An extensive network of local branches allows for face-to-face assistance.
- Rapid funding can occur as early as one hour after the agreement is signed.
- Loan amounts can reach as high as $30,000.
- Certain loan options might require you to respond to a mailer or visit a branch in person.
3. FastLendGo
FastLendGo serves as your digital scout, scouring the landscape of local personal loans so you don’t have to. Instead of spending your entire afternoon on hold with various banks, FastLendGo pulls multiple offers into one easy-to-read dashboard. It’s like having a personal shopper for your financing needs.
The platform is a dream for mobile users who need to make quick moves while on the move. They don’t turn up their noses at bad credit or even a complete lack of credit history. They are built for the person who needs a lender «near me» without the headache of waiting in a bank lobby.
Their system is designed to handle everything from a $500 bandage for a car repair to much larger sums for significant household upgrades. By seeing the whole field at once, you can pick the most competitive rate that fits your unique profile.
Pros:- Supports a massive array of uses, from dental work to vehicle repairs.
- Available to various credit profiles, including those with no credit history.
- Provides an efficient way to compare local lenders side-by-side.
- Functions as a comparison engine, so the final terms are set by the specific lender you match with.
4. Reprise
Reprise is a different beast entirely, operating at the cutting edge of AI-driven data management. While you won’t find them offering personal loans for your monthly bills, they represent the sophisticated side of modern fintech. They are masters of the digital demo and high-level data orchestration.
They are far more a specialized business tool than a consumer lender. For the professional who needs to present flawless, data-driven demos, they offer high-tech features like full clones and seamless data injection. It is a vital part of the tech ecosystem, even if it isn’t for your wallet.
They remind us that as finance becomes more automated, the tools used to manage that data must become equally advanced. They occupy a unique niche in this list, highlighting just how diverse the modern financial technology landscape has become.
Pros:- Utilizes high-end AI technology for creating sophisticated demos.
- Provides powerful capabilities for injecting complex data.
- Streamlines the management of professional presentations.
- Does not act as a traditional consumer lender for personal debt or individual loans.
5. United Finance
United Finance is a seasoned veteran that has been standing firm since 1922. In a world full of flashy, «blink-and-you’ll-miss-them» fintech startups, they offer the comfort of deep-rooted stability. They have weathered decades of economic shifts, which speaks volumes about their reliability.
Their expertise lies in keeping things simple with accessible personal and auto loans. Because they have been around for over a century, they truly understand the rhythms of the lending cycle and how to manage risk effectively. It’s a rock-solid choice for those who prefer tradition over trends.
They offer personal financing up to $20,000 to help you meet your needs. Interestingly, they also offer high-yield certificates for those living in Oregon. This mix of lending and investment products makes them a comprehensive choice for a stable financial future.
Pros:- Boasts an incredible history of longevity and institutional stability.
- Provides both personal and automotive loan options.
- Offers specialized investment tools like high-yield certificates.
- Certain products, specifically investment certificates, may have regional restrictions like Oregon residency.
6. OppLoans
When time is of the essence, OppLoans is built to move at your speed without bruising your credit score. One of their standout features is that the application process won’t trigger a FICO score drop. For someone working hard to climb out of a 500-credit-score hole, this is a massive blessing.
We all know how a «hard inquiry» can sting your score, so being able to shop for eligibility without a penalty is a major win. They partner with various banks to provide rapid decisions, often delivering answers in just a few minutes.
If you are facing an emergency, they offer same-day funding to get you through the crisis. This is perfect for those urgent moments where a 24-hour delay might mean a late fee or a utility disconnection. They are built for the «right now» moments of life.
Pros:- Checking your eligibility does not impact your FICO score.
- Provides same-day funding for those who are approved.
- Features a very rapid decision-making window.
- Primarily designed for immediate, high-need situations rather than long-term wealth building.
Hunting for the Right Borrowing Options
Staring at a 500 credit score can feel like looking into an abyss of rejection. When things feel dire, you might be tempted to leap at the first lifeline that floats your way. However, grabbing the easiest option is often a double-edged sword that cuts deep into your wallet.
It is absolutely crucial to scrutinize the fine print concerning the complete expense of your debt. A quick cash injection might seem like a blessing at first glance. In reality, predatory interest rates can transform a small lifeline into an anchor that drags you down for years to come.
Keep a sharp eye out for «origination fees» during your search. Think of these as a toll taken before you even get started. They are upfront charges deducted directly from the principal you requested from the bank.
Imagine you apply for a $1,000 loan, but the lender decides to shave off a $100 fee right away. You will walk away with only $900 in your pocket. The catch? You are still responsible for paying back the interest on the full $1,000. It is a sting that many borrowers realize too late.
Don’t let the difference between a soft and hard credit inquiry fly under your radar. This is a classic trap for the unwary. You want to find lenders who offer a «soft pull» to check your eligibility first.
Using these no-impact checks allows you to shop around like a savvy consumer. You can compare various rates without further bruising your credit score. Use this window to collect several different quotes. Comparing the APRs across various institutions is the only way to ensure you aren’t overpaying for the simple privilege of borrowing money.
Many people stumble when they fail to weigh the long-term impact of their repayment schedule. It is a delicate balancing act between monthly comfort and total cost. A shorter repayment window keeps your monthly bill high, while stretching the timeline out will increase the total interest you pay over time.
If you opt for a 60-month term just to lower your monthly commitment, the math can get scary. You might find yourself paying back almost twice the original amount you borrowed. This is how a temporary fix turns into a lifelong struggle.
Select a duration that fits snugly within your monthly budget without leaving you bone-dry. You need to leave some breathing room to build up your emergency savings. Ultimately, the goal is to bridge a financial gap, not to fall into a never-ending cycle of mounting debt.

Top rated
-
 Cell phones
$250.00
-
sheath cell phone Samsung A20/ A30/ A50
$8.16
-
sheath cell phone Samsung A20s
$1.00
-
Samsung Bluetooth Headphones
$1.00
-
Xiaomi headphones
$10.00
Products
-
Cell phones
$250.00
-
Anker PowerCore portable charger
$39.99 – $55.99
-
Xiaomi headphones
$10.00
-
sheath cell phone Samsung A20/ A30/ A50
$8.16

